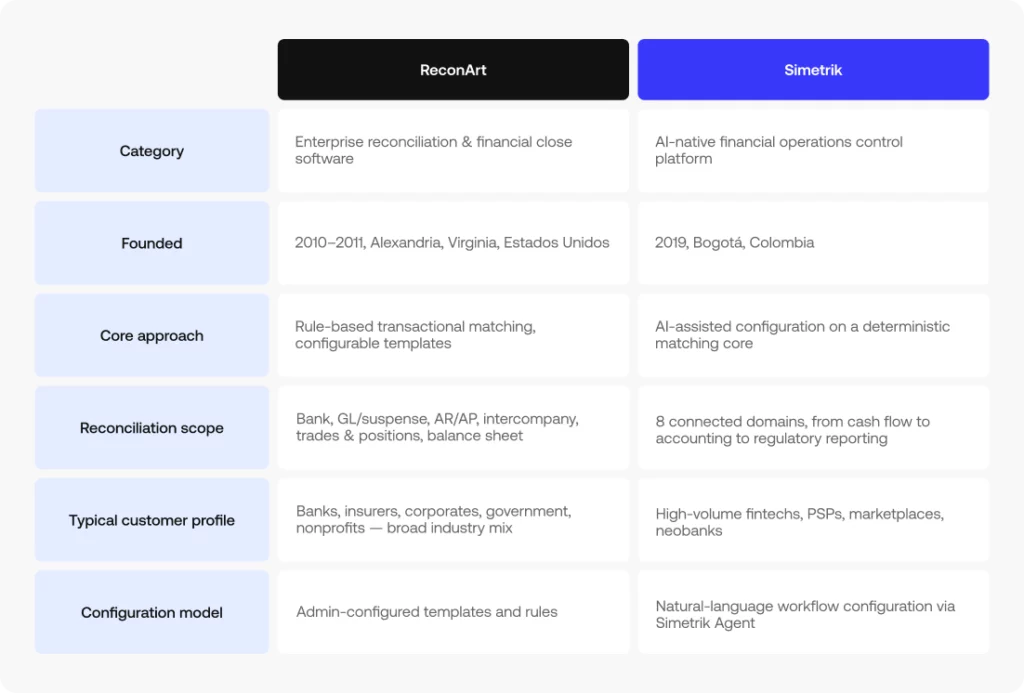
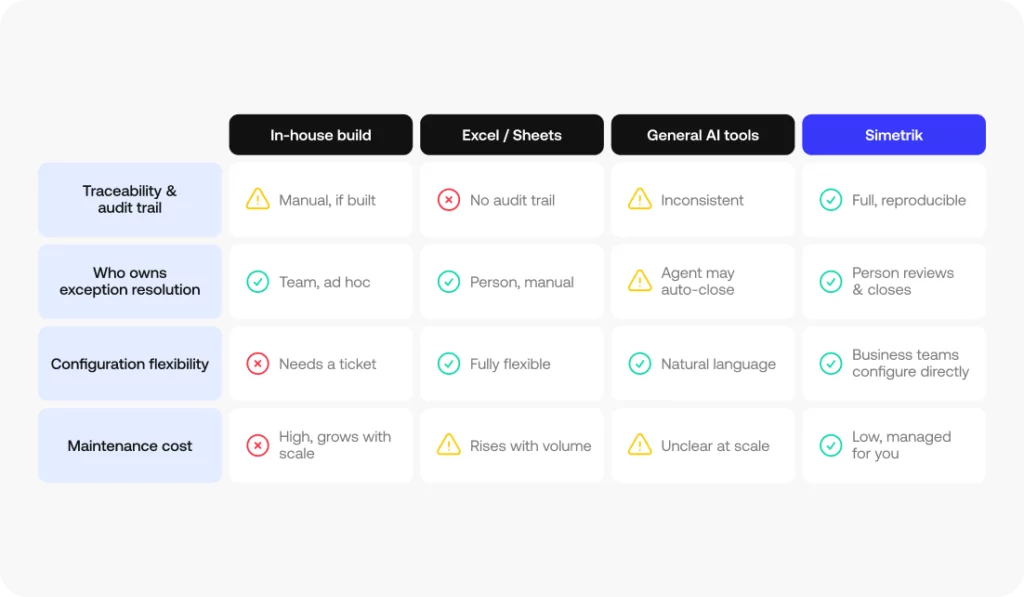
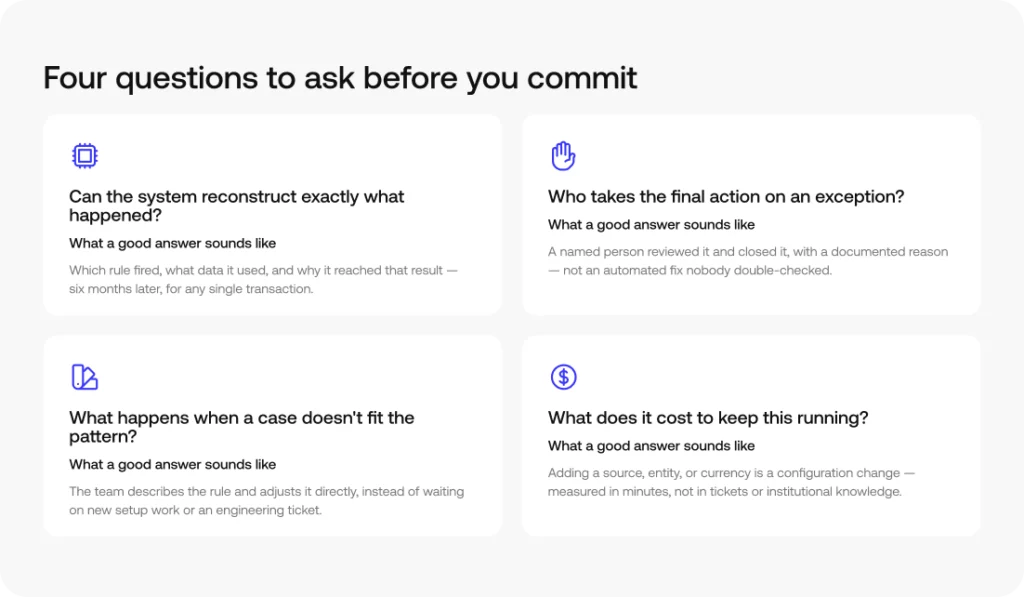
Simetrik and ReconArt are both built to do the same core job: reconcile transaction and account data so finance teams can trust their numbers. Where they differ is how they do it and who they’re built for. ReconArt is a long-established, template-driven platform used across a broad range of industries. Simetrik is the only, AI-native platform built specifically for the high-volume, high-complexity transaction environments common in fintechs, payment processors, and marketplaces.
This guide compares what each platform does, who typically uses it, and how to think about the choice, without going deep into either vendor’s internals beyond what’s publicly documented.
What does ReconArt do?
ReconArt is an enterprise-class, fully web-based reconciliation platform first released around 2010–2011. It’s built to automate the full reconciliation lifecycle: data integration, transactional matching, exception management, and auditable balance sheet reconciliation, plus supporting functions like journal approvals and variance analysis.
ReconArt serves a broad customer base across banks, corporations, insurance companies, government agencies, and nonprofits. Its reconciliation scope covers bank accounts, credit cards, GL/suspense accounts, AR/AP, intercompany balances, and trades and positions, configured through admin-managed templates and rules.
What does Simetrik do?
Simetrik is an AI-native financial control platform organized around 8 connected domains, covering the full transaction lifecycle from cash in and cash out through accounting operations and regulatory reporting. It’s built specifically for high-volume transactional environments: fintechs, payment processors, marketplaces, and neobanks operating across multiple countries, currencies, and data sources.
Where ReconArt’s configuration model centers on admin-managed templates, Simetrik pairs a deterministic matching core with an AI layer, Simetrik Agent, that supports natural-language workflow configuration, letting business teams adjust rules without an engineering ticket for every change.
Simetrik vs. ReconArt at a Glance
How to Think About the Choice
If your reconciliation needs span a broad, traditional set of use cases across a stable, moderate volume of transactions, and you value long-established, template-driven configuration, ReconArt’s breadth across industries is worth evaluating.
If you’re operating at high transaction volume with complex, fast-changing data sources (multiple processors, currencies, countries, or a fast-growing fintech environment), Simetrik’s AI-native configuration and its specialization in high-volume, high-complexity operations is built specifically for that profile.
If you’re comparing more than these two platforms, see our Simetrik alternatives guide, which also covers build-vs-buy, spreadsheets, and general AI tools.
See Simetrik in Action
If your reconciliation needs are outgrowing template-based configuration or manual setup, see how Simetrik handles high-volume, multi-source reconciliation with AI-assisted configuration.
Frequently Asked Questions About Simetrik and ReconArt
Is ReconArt a direct competitor to Simetrik?
Yes. Unlike some other names that come up in “Simetrik vs.” searches, ReconArt is a genuine category peer, both are reconciliation and financial close platforms, and ReconArt appears on public competitor listings for Simetrik.
What’s the main difference between Simetrik and ReconArt?
ReconArt is a longer-established, template-driven platform built for a broad range of industries and reconciliation types. Simetrik is an AI-native platform built specifically for high-volume, high-complexity transactional environments like fintechs and marketplaces.
Does Simetrik use AI differently than ReconArt?
Simetrik pairs a deterministic matching core with an AI layer for configuration, pattern detection, and natural-language workflow setup through Simetrik Agent. ReconArt’s public materials describe a rule-based, template-driven configuration model; whether or how it incorporates AI-assisted configuration is worth confirming directly with ReconArt.
Which platform is better for high-volume fintech reconciliation?
Simetrik is purpose-built for high-volume, high-complexity transactional environments such as fintechs, payment processors, and marketplaces. ReconArt’s customer base spans a broader industry mix, including banks, insurers, and government agencies, without that same specialization.
Can I switch from ReconArt to Simetrik?
Migrations between reconciliation platforms are a technical and operational undertaking specific to each company’s data sources and rules. The right next step is a direct conversation with Simetrik’s team about your current setup.
Artificial intelligence, generative AI, machine learning, agentic AI: the labels pile up faster than most finance teams can evaluate what any of them actually do for their books. Search interest in “AI accounting” has climbed hard over the past year, and for good reason. The opportunity is real. It’s just not evenly spread, and it doesn’t look the same in every part of the finance function.
This is a category map, not a hype piece: where AI is genuinely changing accounting work today, category by category, and where a platform like Simetrik fits into that picture.
What’s Actually Changing in Accounting Teams
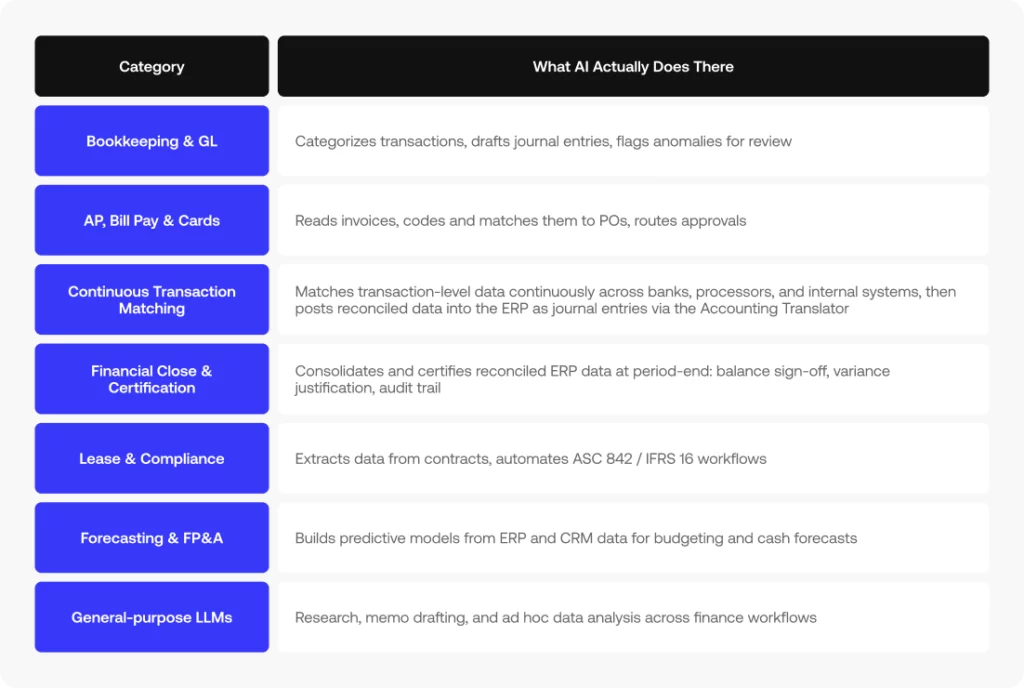
The shift isn’t accounting teams being replaced by AI agents. Its accounting teams increasingly supervising AI agents that handle the first pass on repetitive work, categorizing transactions, drafting entries, matching records, so people spend more time on judgment calls and exceptions and less on data entry. Workflow automation that automates an entire process end to end is still rare. Automating the first 80% of a workflow and routing the rest for review is where most of today’s real adoption sits, and it’s usually described less as one big leap and more as teams learning to automate workflows piece by piece.
Bookkeeping and the General Ledger
AI-native bookkeeping tools now pair automated categorization with human review, aimed at startups that want hands-off books without giving up oversight. At the same time, mainstream small-business accounting platforms have been layering AI-assisted categorization and reconciliation suggestions directly into their existing general ledgers rather than requiring a separate tool.
Accounts Payable, Bill Pay, and Corporate Cards
Purpose-built AP tools now read invoices, code them, match them to purchase orders, and route approvals automatically, aimed at mid-market and enterprise teams processing high invoice counts. Spend-management and corporate-card platforms are approaching the same problem from the other direction, pairing spend controls with AI-assisted invoice processing and bill pay.
Accounts Receivable
Accounts receivable has seen less AI investment than AP so far, but the same shape of automation is starting to show up: matching incoming payments to open invoices, flagging partial payments, and automating collection follow-ups, reducing the manual cash application work that used to eat up a meaningful chunk of the AR function’s time.
Month-End Close, Reconciliation, and Financial Reporting
This is where the stakes are highest, and where the guardrails matter most. Reconciliation and close involve matching transaction data across multiple systems (a bank, a processor, an ERP, a general ledger), flagging what doesn’t match, and producing an audit trail that holds up months later. Anomaly detection helps flag the exceptions worth a human’s attention. Traceability is what makes the result defensible to an auditor.
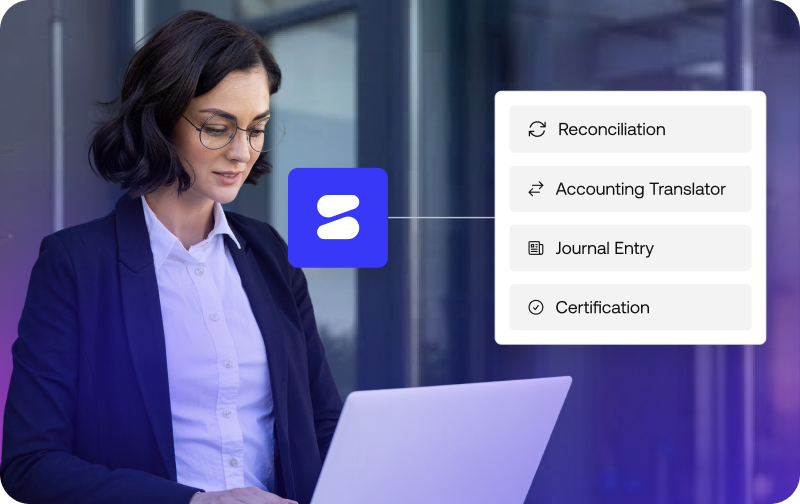
Simetrik operates in exactly this category, built around continuous close rather than a periodic scramble at month-end. A deterministic matching core reconciles transaction-level data continuously, across banks, processors, and internal systems, throughout the month, not just at cutoff. From there, Simetrik’s Accounting Translator turns reconciled data into journal entries and posts them directly into the customer’s ERP, while a structured account reconciliation workflow lets preparers and certifiers compare ERP balances against evidence, document a justification for every variance, and certify each account for the period, with a full audit trail. The result is a close that happens continuously across the month instead of a scramble compressed into a few days at the end of it. See our Simetrik alternatives guide for how this category compares to building in-house, spreadsheets, or general AI tools.
Lease Accounting and Compliance-Heavy Workflows
A newer wave of tools applies AI specifically to lease accounting and revenue recognition compliance, ASC 842 and IFRS 16 in particular, extracting data from contracts and source documents and connecting it to audit trails that link every recognized number back to its source. It’s a good example of AI being applied to a narrow, compliance-heavy workflow rather than the general ledger broadly.
Forecasting, Budgeting, and Predictive Analytics
Forecasting and budgeting tools increasingly pull from ERP and CRM data together, using predictive analytics to project cash flow, revenue, and budget variance rather than relying on a static annual model. The same shift is showing up in wealth management and financial advisory work, where AI-assisted analysis is being used to support (not replace) the judgment a financial advisor brings to a client relationship.
The General-Purpose Layer: LLMs in Finance Work
Alongside all of the above, general-purpose large language models have become a legitimate part of the accounting toolkit for research, memo drafting, and ad hoc data analysis. None of them are built to execute a financial control on their own, and shouldn’t be asked to. Where they add real value is helping a person move faster through analysis and documentation that used to take longer to draft from scratch.
The AI-in-Accounting Landscape at a Glance
Where Simetrik Fits in the AI Accounting Landscape
Simetrik is built for this category end to end: continuous transaction matching, journal entry automation through the Accounting Translator, and account reconciliation and certification through to period close. A deterministic matching core reconciles data daily across banks, processors, and internal systems. The Accounting Translator carries that reconciled data through to journal entries in the ERP, and a structured certification workflow, preparer and certifier sign-off, evidence attachment, and variance justification, closes each account for the period with a full audit trail.
An AI layer supports natural-language configuration, pattern detection, and exception review, without letting a probabilistic model make the final call on a financial control. The result is a close that runs continuously through the month rather than a scramble compressed into the final few days. It’s designed for high-volume, high-complexity transactional environments, fintechs, payment processors, marketplaces, where reconciling data across many sources is the daily reality, not an edge case.
Simetrik at Money20/20 USA 2026
Money20/20 USA runs October 18–21, 2026, in Las Vegas, bringing together the global payments and fintech ecosystem to talk about what’s next. Book a meeting
See Simetrik’s AI Layer in Action
If reconciliation and close are where your team is still doing the most manual work, see how Simetrik’s deterministic core and AI-assisted configuration handle it at scale.
Frequently Asked Questions About AI in Accounting
What is AI accounting?
AI accounting refers to using machine learning and generative AI to automate accounting tasks, transaction categorization, invoice coding, reconciliation, anomaly detection, and reporting, that traditionally required manual data entry and review.
Will AI replace accountants?
The current pattern is AI handling first-pass, repetitive work while people supervise exceptions and make the final judgment calls, not full replacement. Financial controls in particular still require a human decision on anything a deterministic system can’t resolve automatically.
What’s the difference between AI accounting software and agentic AI?
AI accounting software typically uses machine learning for specific tasks like categorization or anomaly detection. Agentic AI goes further, taking multi-step actions toward a goal, like an AP agent that reads an invoice, matches it to a PO, and routes it for approval without a person initiating each step.
Can general AI tools like ChatGPT or Claude replace dedicated accounting software?
No. General-purpose LLMs are useful for research, drafting, and analysis, but they aren’t built to execute reproducible financial controls. A reconciliation or close process needs a deterministic system that produces the same result from the same inputs every time, which is a different architecture than a conversational AI model.
Where does reconciliation fit in the AI-in-accounting landscape?
Reconciliation and financial close are related but distinct steps: continuous transaction-level matching throughout the month, followed by account-level certification and sign-off at period-end. Simetrik covers both, so certification at close works from data that’s already been reconciled, not from scratch.
Financial close software is a tool that automates the financial close (the process of reconciling accounts, posting journal entries, and producing financial statements at the end of a period). It helps finance teams close the books faster, with fewer errors and a clear audit trail.
This guide walks through what the financial close process actually involves, what financial close software does day to day, the benefits of automating it, the types of tools available, and how to evaluate one for your team.
What is the financial close process?
The financial close process is the set of steps a finance team runs at the end of every period, usually monthly, quarterly, and annually, to finalize the financial record known as the books. It typically culminates in the month-end close: the point where all transactions for the period are recorded, accounts are reconciled, and financial statements are ready to report on.
The month-end close, step by step
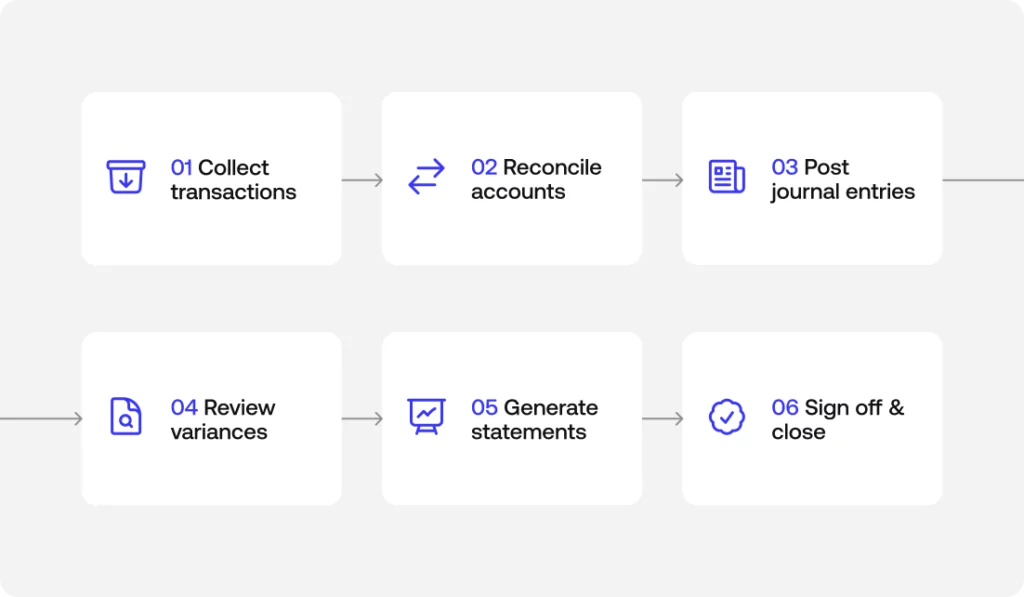
Every close looks a little different depending on company size and complexity, but most follow a similar sequence:
Collect and record all transactions for the period.
Reconcile accounts, matching internal records against bank statements, payment processors and other systems of record.
Post journal entries and accruals for revenue or expenses that belong in the period but haven’t been recorded yet.
Review variances and make adjusting entries where numbers don’t tie out.
Generate financial statements: the balance sheet, income statement, and cash flow statement.
Review and sign off, closing the period.
Keeping this process consistent, and documented, is what makes each close faster and more predictable than the last.
A financial close checklist finance teams use
A simple checklist keeps nothing from slipping through the cracks during a close:
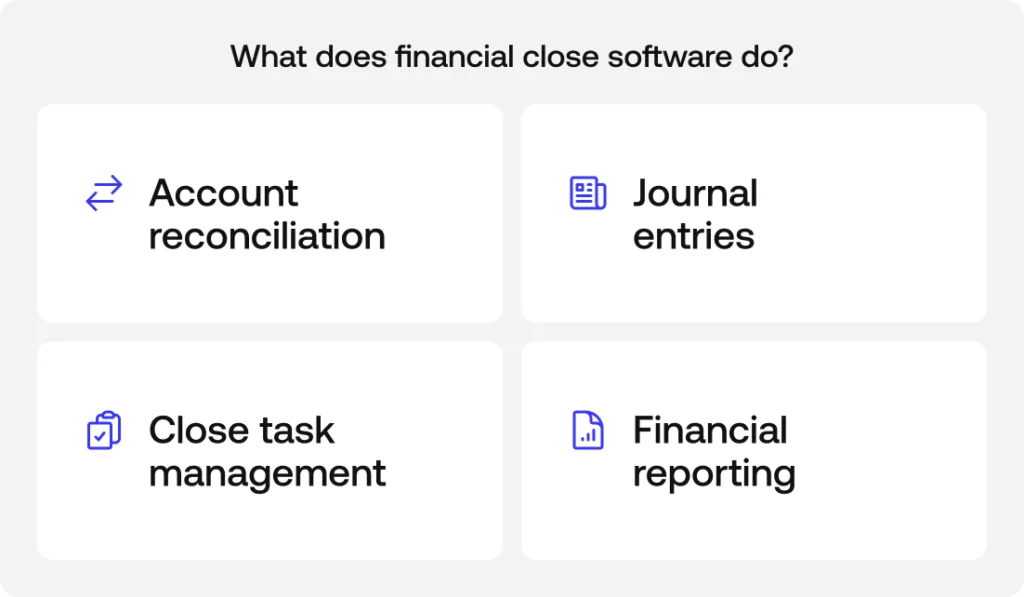
At a high level, financial close software automates the manual, repetitive parts of the close so finance teams spend less time chasing numbers in spreadsheets and more time reviewing exceptions. Most tools in the category cover four core capabilities.
See how Simetrik handles each of these capabilities on a single platform: Request a demo.
Account reconciliation and transaction matching
Financial close software handles account reconciliation and transaction matching automatically, comparing records across systems (banks, payment processors, ERPs) instead of requiring someone to line up rows by hand. This is usually where the biggest time savings show up, since manual reconciliation is one of the most labor-intensive parts of a close.
Journal entries, accruals, and intercompany eliminations
The software can automate the creation of journal entries, accruals, and intercompany eliminations, applying consistent rules so entries are recorded the same way every period instead of depending on one person’s memory of how it was done last time.
Close task management and audit trails
Beyond the numbers, financial close software helps coordinate the close itself: assigning tasks, tracking what’s done and what’s pending, and maintaining audit trails and internal controls so every action taken during the close is logged and traceable.
Financial reporting and financial statements
Once the period is reconciled and adjusted, the software posts the final entries to the general ledger and produces financial statements, the balance sheet, income statement, and cash flow statement, along with the financial reporting finance teams need for management and, eventually, for auditors.
What are the benefits of financial close automation?
Automating the close doesn’t just save time. Finance teams that move away from manual, spreadsheet-based closes typically see:
A faster close, from weeks down to days
Fewer manual errors, since matching and postings follow consistent rules
Better auditability, with every entry and adjustment logged
More visibility into where the close stands at any point, not just at the end
Less manual, repetitive work for the finance team
Types of financial close software
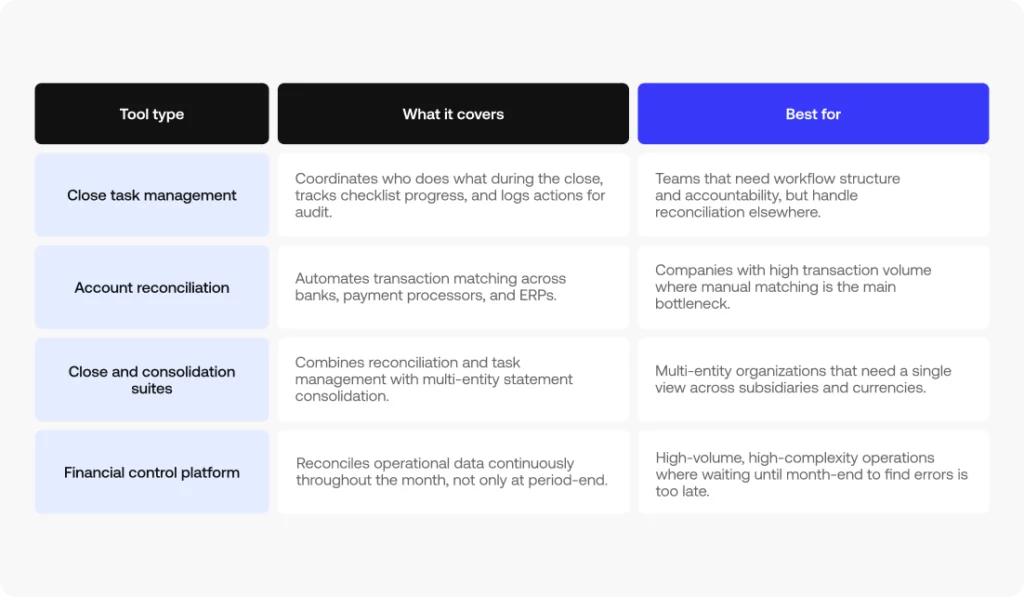
Not every tool in this category does the same thing. Broadly, financial close software falls into a few types:
Close task management tools, which focus on coordinating who does what during the close and tracking progress against a checklist.
Account reconciliation tools, focused specifically on automating the matching of transactions and balances across systems.
Close and consolidation suites, which combine reconciliation and task management with the ability to consolidate financial statements across multiple entities.
Financial control platforms, which go a step further and reconcile operational data continuously, before the close even starts, rather than only at period-end.
Which type makes sense depends on how much of the process you want to automate, and how complex your entity structure and transaction volume already are.
How to evaluate financial close software
A few criteria tend to separate tools that hold up at scale from the ones a finance team outgrows quickly:
Reconciliation depth: does it match at the transaction level, or only confirm that summary balances agree?
Anomaly detection: can it flag unusual patterns on its own, or does someone need to know what to look for?
Multi-entity and IFRS support: does it handle multiple entities, currencies, and accounting standards without manual workarounds?
Audit trails and internal controls: is every action logged, with clear segregation of duties?
ERP integration: how easily does it connect to the systems you already use?
Real automation vs. assisted automation: how much of the close does it actually take off your plate, versus just organizing the manual work?
How continuous close reduces month-end scramble
Traditionally, reconciliation happens after the period ends, which is why closes tend to compress into a stressful few days. Continuous close flips that: operational data gets reconciled throughout the month, as transactions happen, so by the time the period ends, most of the work is already done. The close becomes a final review instead of a race against the calendar.
What is the difference between financial close and consolidation?
The financial close finalizes one entity’s books for a period; financial consolidation combines multiple entities into group financial statements. Close comes first; consolidation builds on it.
How long should the financial close take?
It varies by company size and complexity, but many teams aim to close within a handful of business days. Automating reconciliation and journal entries is what shortens it.
What does financial close management software do?
It coordinates the close: reconciling accounts, automating journal entries and accruals, tracking close tasks and controls, and producing audit-ready financial statements from verified data.
See financial close software in action
If you’d like to see how this works on an actual platform, Simetrik applies financial close software across account reconciliation, close task management, and reporting for high-volume, multi-entity operations. Book a demo to walk through how it applies to your own close.
Most “best software” roundups compare vendors by name. This breakdown of the key features of financial reporting software takes a different approach: what the software should actually do, independent of any specific financial reporting tools or financial reporting solutions on the market today.
The key features of financial reporting software fall into seven areas: core financial statements, forecasting and KPIs, dashboards and custom reporting, data integration, compliance controls, cross-functional reporting, and AI-native automation. The right mix depends on how complex your entities, currencies, and audit requirements are.
The sections below walk through each area, what to look for, and why it matters.
Core Financial Statement Features in Financial Reporting Software
These are the base outputs any financial statement software has to produce without manual rework, the statements a finance team builds every close whether anyone asks for them by name or not. This is the first place where financial statement reporting software and management reporting software earn their keep.
Cash flow, balance sheet, and income statement reporting
A finance team closing the books by hand ends up rebuilding the same three statements every period: the cash flow statement, the balance sheet, and the income statement. Reporting software generates all three automatically from data that has already been reconciled, broken out by period, entity, or business line, instead of starting from a blank spreadsheet each time. That includes profit and loss statements that stay comparable across periods, with drill-down back to the source transaction whenever a number needs explaining.
General ledger sync and management reporting
Waiting for a batch export at month-end to see what the general ledger sync says is a bottleneck, not a control. Reporting software syncs with the general ledger continuously, so management reporting reflects what has actually happened, not what happened as of the last upload. It also builds management reporting around what each area lead needs to see, rather than a single template that gets reinterpreted by whoever is building the deck, or an analyst manually assembling it every cycle.
Forecasting, KPI, and Scenario Planning Tools
Reporting on the present table stakes. The next layer, the territory of financial statement software and financial reporting and analysis software, is where FP&A teams live: using that same data to project what is coming, decide what to do about it, and turn recurring reporting into ongoing performance management.
Forecasting, KPI tracking, and variance analysis
Forecasting built on real historical data holds up better than one built on a spreadsheet’s assumptions, because it inherits the same granularity as the underlying transactions instead of averaging it away. Reporting software should project revenue, expenses, and cash flow from that data, track the KPIs each finance team has defined as critical using real-time data instead of a month-end snapshot, and run variance analysis automatically, comparing actual results to budget and flagging which deviations are worth a second look instead of leaving that triage to whoever notices first.
Simetrik’s Unified Oversight & Alerts domain, for instance, offers customizable dashboards that track real-time KPIs and intelligent alerts on anomalies, built on top of data that has already been reconciled.
Scenario planning, modeling, and BI integration
Scenario planning lets a finance team model the impact of a decision before making it. That means scenario modeling that can handle multiple variables at once, volume, FX rates, and cost changes. Without leaning on formulas that break the moment someone edits the wrong cell. It also means a real connection to business intelligence tools, so financial data feeds the same analysis layer used for decision making across the rest of the company, instead of living in its own silo.
Dashboard and Data Visualization Capabilities
How the data gets consumed matters as much as how it gets produced, which is the whole premise behind financial dashboard software.
Data visualization and customizable dashboards
A finance team can read a spreadsheet. Nobody else in the company necessarily wants to. Good reporting software translates the same figures into data visualization that a non-financial stakeholder can understand in seconds, without waiting on an analyst to build the chart. That means customizable dashboards by role, since a CFO and a controller do not need the same default view, and interactive dashboards that let someone filter and explore the data themselves instead of requesting a new cut from finance every time a question comes up, the core idea behind self-service reporting.
Customizable, custom, and cash flow reports
Every stakeholder expects a different format, and forcing all of them into the same template just means more manual reformatting later. Reporting software should offer customizable reports that adapt to what each audience actually needs, plus the ability to build custom reports for one-off questions from leadership that do not fit a recurring template. Cash flow reports deserve extra attention: treasury generally needs a level of transactional detail that does not belong in a high-level accounting deck.
Data Integration and Connectivity Features
None of the above works without a reliable answer to where the data actually comes from. That’s the core promise of automated financial reporting software: reports built on data pulled directly from source systems, via cloud-based software that plugs into what a company already runs.
Data integration and API connectivity
Manually exporting from one system and importing into another is where reporting errors quietly start. Reporting software should handle data integration between ERPs, banks, and payment processors through direct API connectivity, plugging into the systems a company already runs, whether that is an ERP like NetSuite or QuickBooks, rather than forcing a full migration just to get clean data into a report.
Bank feeds, reconciliation, and multi-currency consolidation
Downloading a bank statement and reconciling it by hand is still how a lot of finance teams operate, and it is slow by design. Reporting software should bring in bank feeds directly and automate bank reconciliation as part of the same pipeline that feeds the reports, rather than treating it as a separate manual step. For companies operating in more than one currency, that also means real data consolidation, multiple sources and currencies resolved before the numbers ever reach the final report, with genuine multi-currency support instead of a manual conversion step.
Compliance, Audit, and Regulatory Control Features
Regulatory compliance and audit readiness are not features to bolt on later; they are an output of how the rest of an enterprise financial reporting software platform is built.
Audit trails and GAAP/IFRS compliance
An auditor does not want a summary number; they want to trace it back to where it came from. Reporting software needs to leave audit trails for every figure in every report.This needs to be traceable to its source transaction, and support reporting aligned to GAAP or IFRS depending on the jurisdiction. Without the finance team rebuilding accounting logic by hand for each country it operates in.
Role-based access and approval workflows
Not everyone who touches the numbers should be able to edit them. Role-based access limits what each user can see and change based on their role, and approval workflows chain together the sign-offs a report or adjustment needs before it is considered final, with a record of exactly who approved what and when.
Tax management and version control
Tax management gets easier when the underlying data is already reconciled and traceable, instead of assembled specifically for the tax team after the fact. Version control matters just as much: knowing what changed between one version of a report or model and the next, and who changed it, is the difference between a controlled process and a guessing game during review.
Operational and Cross-Functional Reporting Features
The last layer of financial management reporting software connects financial reporting to the parts of the business that do not sit inside finance but still show up in the numbers.
Expense and inventory management integration
Expense management should not live in a separate system that finance re-keys into the reports by hand. Reporting software should connect the two so approved expenses show up without double entry. The same logic applies to inventory management for any business whose financial statements depend on what is actually on the shelf: physical stock and financial reporting need to stay in sync, not get reconciled after the fact.
Project-based reporting and multi-entity support
Project-based reporting applies the same tracking logic project management tools use, but for financial control rather than task management, so a project’s costs and revenue can be reported on its own terms. Multi-entity support does the equivalent across the company as a whole: consolidating reporting across subsidiaries or separate legal entities without manually stitching together spreadsheets from each one.
AI-Native Financial Reporting Software Features
This is the newest layer, and the one where the gap between financial reporting software that is genuinely AI-native and financial reporting software that only added a chatbot on top actually shows.
AI-ready data ingestion and AI-suggested matching
Most financial data is not clean by default; it arrives with gaps, inconsistent formats, and fields that do not map neatly to anything. AI-native reporting software should prepare that data automatically before it reaches any report or dashboard, closing gaps and fixing inconsistencies without a person cleaning it row by row. It should also suggest transaction matches that fixed, rule-based logic misses, learning from patterns that do not follow a standard format instead of requiring someone to write a new rule for every exception.
Simetrik describes its own data layer as designed to get data AI-ready: the platform automatically cleans data and fills in gaps with the help of agentic AI. Its reconciliation engine includes AI-suggested mappings, automatic FX handling, and AI-driven payment-to-invoice mapping.
Agent-driven exception management and AI-generated reports
What happens when something does not match? In this event, AI-native platforms route exceptions to agents that prioritize and work through them, instead of dumping everything into one unsorted queue for a person to triage manually. On the reporting side, that same layer can draft reports adjusted to the relevant regulatory standard directly from already-reconciled data, not raw data, cutting out a step that used to require someone to manually reformat numbers into a compliance template.
Simetrik, for example, includes built-in fraud detection algorithms and agent-driven risk management within its exception management module, and generates AI-generated, standard-specific documents backed by fully traceable, exportable audit logs.
See AI-native reporting on your own reconciled data
Every feature in this section, AI-ready ingestion, AI-suggested matching, agent-driven exceptions, AI-generated reports, runs on Simetrik’s reconciliation platform today. If audit-ready reporting is the bottleneck, this is worth a 20-minute look.
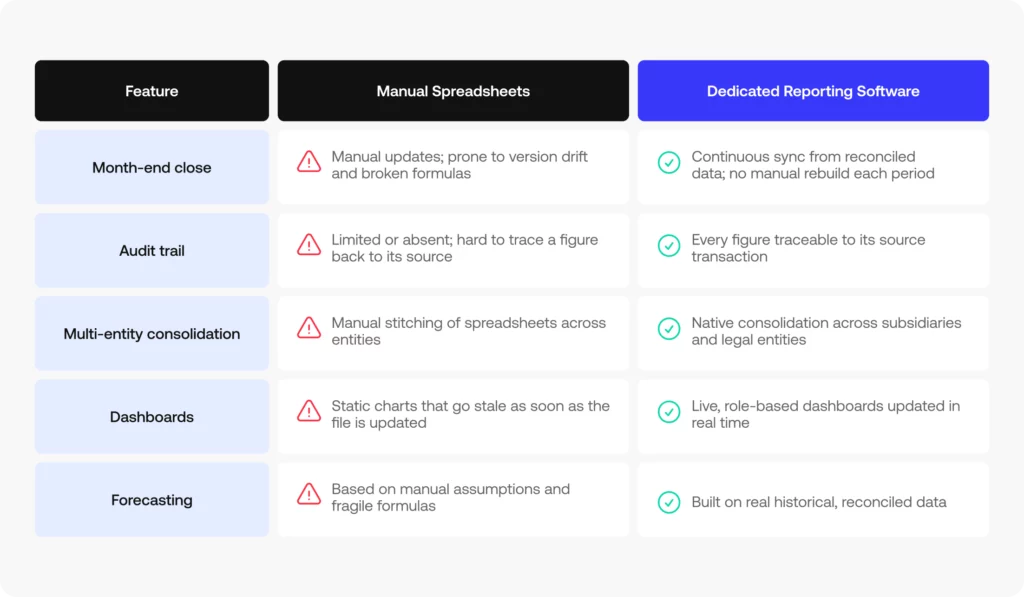
Financial Reporting Software vs. Manual Spreadsheets: A Feature Comparison
Spreadsheets are not the enemy of good reporting software; they simply were not built to do this at scale. Here is where the two approaches diverge on the features that matter most in any financial report software evaluation:
Financial Reporting Software FAQs
A few of the questions finance teams ask most often when comparing financial reporting solutions and weighing the key features of financial reporting software against what is sold as the best financial reporting software on the market:
What is financial reporting software?
Financial reporting software pulls data from accounting systems, banks, and operational tools to generate financial statements, dashboards, and reports automatically, instead of building each one manually in a spreadsheet.
What features should financial reporting software have?
At minimum: core statements (cash flow, balance sheet, income statement), forecasting and KPI tracking, customizable dashboards, data integration via APIs, and audit trails for compliance. The right depth depends on entity count, currencies, and audit requirements.
Does financial reporting software replace spreadsheets entirely?
It replaces the manual assembly of recurring reports, not every ad hoc analysis. Most finance teams still export data for one-off modeling, but the recurring statements and dashboards stop depending on manual updates.
How is financial reporting software different from accounting software?
Accounting software records transactions and manages the books. Financial reporting software sits on top of that data (and other sources) to produce statements, dashboards, and analysis; some platforms combine both, others specialize in reporting only.
Which features matter most as a finance team scales?
Multi-entity support, multi-currency handling, role-based access, and audit trails become priorities as headcount, entities, and regulatory exposure grow, features that matter less for a single-entity, single-currency business.
Next Step: Evaluate These Financial Reporting Software Features
Now that you have the full checklist of features, the next step is contrasting it against your current reporting stack to see where the real gaps are, whether you are benchmarking against the top financial reporting software on the market or evaluating financial reporting solutions for the first time. See how these controls connect to Simetrik’s financial reporting software built on reconciled data end to end reconciled data.
Agentic commerce is commerce where an AI agent acts on a person’s behalf across some or all of the shopping journey: finding a product, comparing it against alternatives, and completing checkout, without the person clicking through a website themselves. It’s a change to how online shopping happens, not a new product category on top of it.
It’s what you get when agentic AI, a branch of artificial intelligence built to plan and carry out multi-step actions toward a goal rather than just answer a question, gets applied to buying and selling. The person still sets the intent: “find running shoes under $100,” “reorder the coffee I usually get.” From there, an autonomous agent, sometimes a chatbot, sometimes an AI assistant built into a browser or an app, and increasingly one of a growing set of intelligent agents built for this specifically, does the researching, comparing, and transacting.
None of the underlying pieces are new by themselves. Generative AI and large language models (LLMs) that can reason over messy, unstructured text have been around for a few years. Conversational interfaces that swap a search bar for a chat window aren’t new either. What changed is combining generative AI, automation, and enough shared infrastructure between AI platforms and merchants to actually complete a transaction, not just recommend one.
How Agentic Commerce Actually Works
The mechanics break down into three stages, and each one depends on the merchant and the agent agreeing on a common format.
Product discovery. Instead of typing into a search box, a person describes what they want to a chatbot or AI assistant. The agent pulls from product feeds and structured product data, titles, prices, availability, variants, shipping details, that merchants expose through APIs. If that data is incomplete or stale, the agent either surfaces the wrong thing or fails quietly. There’s no person eyeballing a product page to catch the mismatch.
Comparison and decision-making. The agent weighs price, reviews, availability, and delivery time, sometimes across more than one retailer or marketplace, and narrows it down. Depending on how it’s configured, it might ask a clarifying question or just present its best option.
Checkout and payment. Once the person confirms, the agent completes the purchase using a payment token, a stand-in credential scoped to that agent, that merchant, and usually that specific transaction, rather than the person’s real card number. The merchant still gets paid the way it always has. The token is what lets the agent transact without holding a real card number, and it’s also what lets a bank shut off one agent’s access without touching the person’s underlying card.
The Protocols Behind It: ACP and UCP
For an agent to buy from a merchant it’s never dealt with before, both sides need to speak the same language: how a product is described, how a cart is built, how a payment credential gets passed along. That’s the job of the open standards emerging around agentic commerce, most visibly the Agentic Commerce Protocol (ACP) and the Universal Commerce Protocol (UCP), the two standards currently shaping this next stage of digital commerce.
ACP was released by OpenAI and Stripe in September 2025. It powers Instant Checkout inside ChatGPT, starting with Etsy sellers and expanding to Shopify merchants. It’s an open standard rather than a proprietary API limited to those two companies, and it’s built specifically around the conversational checkout session: building a cart, applying a payment token, confirming an order.
UCP came from Google, announced in January 2026 and co-developed with retailers including Shopify, Etsy, Target, Walmart, and Wayfair, with more than 20 companies across payments and retail endorsing it, Mastercard and Visa among them. Where ACP centers on the checkout moment inside a chat, UCP is meant to work across a broader set of surfaces, Search’s AI Mode, Gemini, and product discovery generally, plus post-purchase support like order tracking.
The two aren’t really rivals so much as different layers of the same shift, which is small comfort to a retailer deciding which one to integrate, or, more realistically, both, on top of whatever a payment network requires. The alternative, a custom integration for every AI platform a merchant wants to sell through, is exactly the problem open standards exist to avoid. In practice, most retailers will end up supporting more than one protocol regardless.
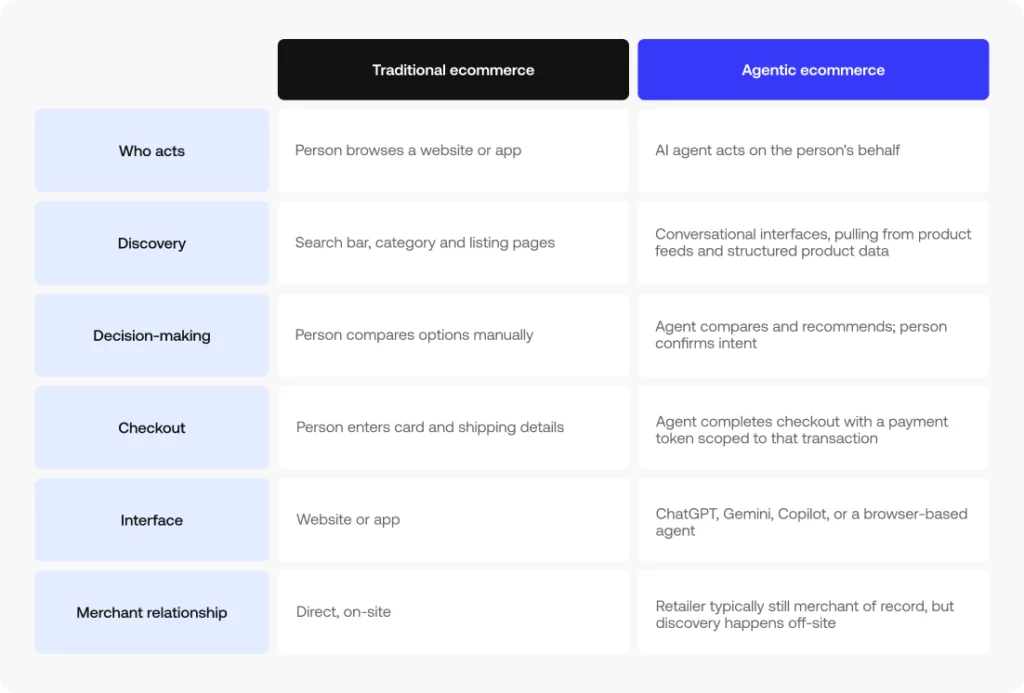
Agentic Commerce vs. Traditional Ecommerce
Who’s Building Agentic Commerce
OpenAI built Instant Checkout into ChatGPT on top of ACP. Google is rolling UCP-powered checkout into Gemini and AI Mode in Search. Microsoft launched its own Copilot Checkout in partnership with Shopify. Perplexity took a different route with Comet, a browser-based agent built for autonomous shopping that can navigate and act across sites, including ones that haven’t opted into any protocol, using the same session a person would use themselves.
That last approach has run into resistance. Amazon does not support third-party shopping agents browsing its site the way Comet does, and the dispute between the two companies has become one of the first real tests of what authorization actually means once AI agents are the ones showing up at checkout.
Where Agentic Commerce Gets Complicated
Who’s actually authorized to be there. Amazon sued Perplexity in late 2025, arguing Comet accessed its site without permission and made it harder to separate real shoppers from automated traffic before that traffic reached advertisers. A federal judge agreed in March 2026 and temporarily blocked Comet from accessing Amazon accounts. The Ninth Circuit later lifted that block, ruling that it’s the person using the agent, not the software itself, that counts as “accessing” the site. Perplexity kept fighting the underlying case. Whatever the final outcome, the dispute previews a question every platform with agentic traffic is going to face: does a person’s permission to their own AI agent override a platform’s right to decide who gets in.
Fraud detection has to relearn what normal looks like. Most fraud models are trained on how people behave: mouse movement, session timing, device fingerprints, browsing patterns. An autonomous agent doesn’t move like a person, which means the systems built to catch bots now have to tell a bad actor apart from a legitimate agent transacting on someone’s real behalf. Amazon’s complaint against Perplexity leaned on exactly this point, arguing it had to build new filtering just to keep AI-generated traffic from skewing what it charges advertisers.
Structured data stops being optional. A person who hits a “sold out” banner understands what happened and looks for something else. An agent handed bad inventory data can quietly fail the checkout, or worse, complete it and create a fulfillment problem downstream. Accurate product feeds and metadata aren’t just a ranking input anymore; they’re closer to a revenue requirement, and it’s part of why agentic commerce overlaps with GEO. The same structured, accurate product information that helps an agent complete a purchase is what helps a generative engine cite that product in an informational answer in the first place.
Interoperability means picking more than one standard. If every AI platform and every retailer needed a custom integration with each other, the math doesn’t work, which is exactly why ACP and UCP exist. But supporting an open standard isn’t free, and most retailers will end up integrating with more than one, plus whatever tokenization a given card network requires on top. The complexity doesn’t stop at checkout, either: supply chain and fulfillment still have to handle the exceptions, wrong size, canceled order, duplicate purchase, that used to get caught by a person reviewing their own cart before hitting buy.
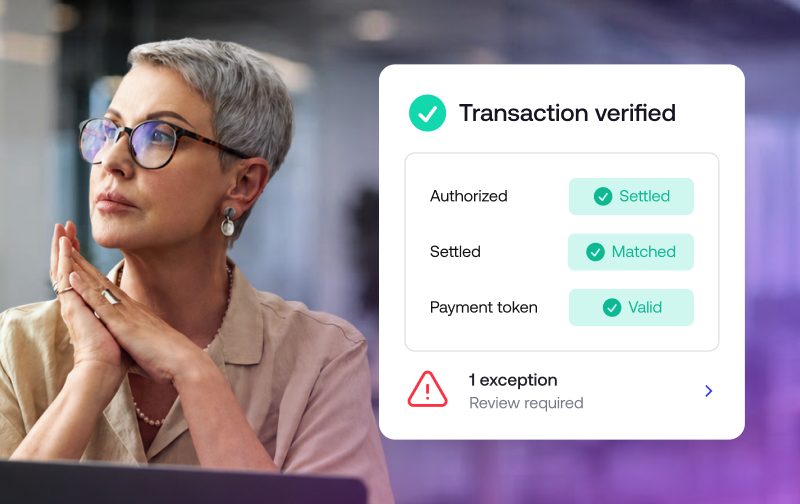
Subscriptions, pricing, and the reconciliation gap. When an agent renews a subscription or accepts a price on someone’s behalf, somebody still has to confirm the charge matches what was actually authorized, at the price that was actually agreed to, and reconcile it against what settled. Multiply that across two or three commerce protocols, several payment tokens formats, and transactions no person saw happen in real time, and the operations problem gets harder, not easier. This is where mismatched authorizations, duplicate charges, and disputes tend to surface, usually well after the fact, and usually as a number that doesn’t match at close.
The Part That Doesn’t Show Up in the Demo: Financial Control
None of the reconciliation problem above disappears because a transaction started with an AI agent instead of a person clicking “buy.” It just becomes less visible until it shows up as a chargeback, a duplicate charge, or a settlement file that doesn’t match what was authorized.
That’s the layer Simetrik works in. Simetrik was recently selected for Mastercard Start Path’s inaugural Agentic Commerce and Services cohort, a program built for companies working on the infrastructure behind AI-driven transactions.
As an AI-native financial control platform, Simetrik can function as a control layer between the records generated by processors, banks, and internal systems, comparing what was authorized against what actually settled and routing the differences for investigation, regardless of which protocol or AI platform initiated the transaction.
The same interoperability problem shows up on the infrastructure side, too. Simetrik connects with external agents and workflows through MCP, the same kind of open connection standard that both ACP and UCP support for linking agents to backend systems, so reconciliation and control work can plug into the tools a finance or operations team already uses.
Agentic commerce is still early. The protocols are still settling, the legal questions are still being argued, and most merchants are still deciding which standards to support. What isn’t going to change is that every one of these transactions eventually needs to be verified.
It’s when an AI agent shops and pays for something on your behalf, instead of you clicking through a website or app yourself.
What’s the difference between agentic commerce and traditional ecommerce?
In traditional ecommerce, a person browses a site or app and completes checkout manually. In agentic commerce, a person states what they want to a chatbot or AI assistant, and an autonomous agent handles discovery, comparison, and checkout, usually through a conversational interface rather than a storefront.
What’s the difference between ACP and UCP?
ACP (Agentic Commerce Protocol), built by OpenAI and Stripe, focuses on the checkout session inside conversational surfaces like ChatGPT. UCP (Universal Commerce Protocol), built by Google with a group of retailers and payment companies, covers a wider set of surfaces, including Search and Gemini, across discovery, checkout, and post-purchase support. Most retailers are expected to need both.
Who is the merchant of record when an AI agent makes a purchase?
Under both ACP and UCP, the retailer typically remains the merchant of record. The AI platform provides the interface and the agent, but the sale, the customer relationship, and the settlement still belong to the merchant.
Is agentic commerce safe?
It’s early enough that the safety questions, especially around authorization and fraud detection, are still being worked out. Payment networks address part of this with tokenized credentials scoped to a specific agent and merchant, so a person can revoke an agent’s access without exposing their actual card. Whether an agent is allowed on a given site at all is a separate, ongoing legal question.
How does agentic commerce affect financial reconciliation?
Transactions started by an agent still need to be verified against what settles, the same as any other transaction, but with fewer human touchpoints along the way to catch mismatches early. That makes reconciliation and financial control more important, not less, as agentic commerce scales.
The company will join 21 other businesses from around the world building the infrastructure for a new generation of experiences powered by AI agents.
San Francisco. Simetrik has been selected to participate in Mastercard Start Path’s inaugural Agentic Commerce and Services cohort. The program brings together companies from around the world developing AI-driven solutions across payments and commerce, ranging from agent platforms and enablement tools to emerging agentic payment flows.
This marks the second time Simetrik has been selected for a Mastercard Start Path program, just months after joining its Corporate Solutions track. The new cohort is the first Start Path program focused specifically on Agentic Commerce and Services.
The selection comes as Simetrik advances its vision for agentic financial control. In August, the company launched Simetrik Agent, an autonomous agent that automates financial reconciliation and control tasks while operating on a deterministic, auditable core designed to keep people in control of critical decisions.
As AI agents move beyond recommendations and begin executing transactions, finance teams will need a reliable way to track what happened across increasingly autonomous workflows. Simetrik is building the financial control layer for this new environment, enabling companies to reconcile transactions, detect exceptions, and preserve a complete audit trail.
This work already operates at global scale: more than 180 companies across over 50 countries use Simetrik to process 2.5 billion records every day. Through Mastercard Start Path, the company will tap into Mastercard’s global network, receive tailored support, and have the opportunity to explore new ways to strengthen financial control across the emerging agentic commerce ecosystem.
For Simetrik, joining the program is an opportunity to help shape how companies maintain visibility, traceability, and control as AI agents take on a larger role in transactions.
Mastercard Start Path is Mastercard’s global startup engagement program. Since its launch in 2014, it has supported more than 500 companies across over 60 countries. Participating companies have gone on to raise an estimated $25 billion in post-program capital, while Start Path has facilitated more than 15,000 connections between startups and Mastercard customers and partners worldwide.
About Mastercard Start Path
Mastercard Start Path is a global startup engagement program that partners with later-stage startups and fintech innovators to accelerate growth. Since inception, the program has supported over 500 companies from 60 countries, providing access to Mastercard’s technology, expertise, and global network. Learn more at mastercard.com/startpath.
About Simetrik
Simetrik is an AI-powered financial control infrastructure. Its mission is to give finance teams the control to operate with speed, accuracy, and confidence in an increasingly complex environment. With an autonomous agent backed by a deterministic, auditable core, Simetrik automates complex reconciliations and end-to-end financial controls, and provides a single source of truth over which people retain full control. Today, more than 180 leading companies across 50+ countries trust Simetrik to process 2.5 billion daily records, cut losses, and accelerate growth.
Choosing a reconciliation software comes down to one question: can it match your transactions at the level and volume you actually operate at? Start with automation depth and data coverage, then weigh controls, traceability, scalability, and time-to-value.
Every vendor call will tell you their tool is intelligent, fast, and easy to implement. None of that tells you whether it will hold up on your data, at your volume, under an audit.
This guide walks through the seven criteria that actually predict that, a checklist you can take into your own evaluation.
You’ll also find the questions worth asking vendors, the red flags to watch for, and how the right answer shifts depending on your team and industry.
What reconciliation software should do
Strip away the marketing language and the category does three things:
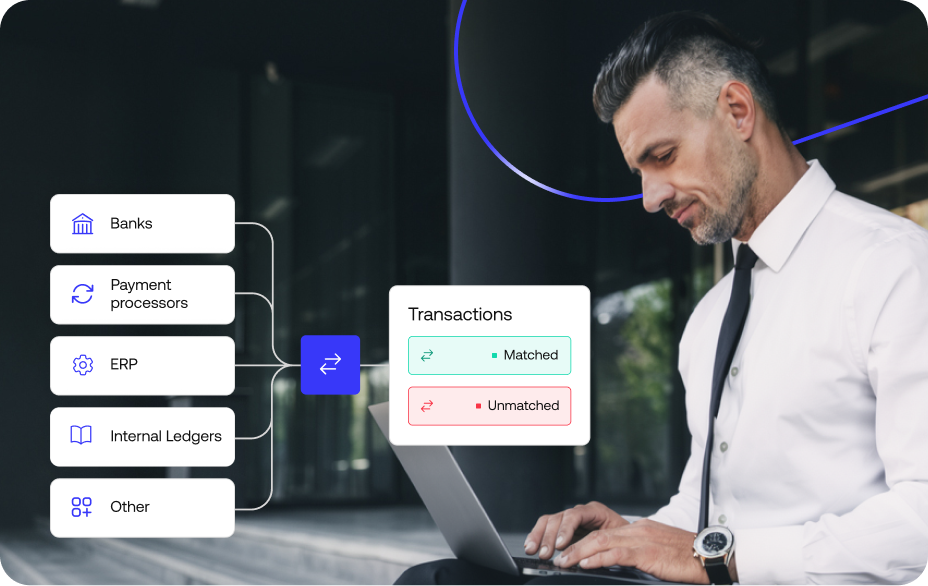
It matches transactions and records across systems (bank statements, payment processors, ERPs, internal ledgers) without someone lining up rows in a spreadsheet by hand.
It flags what doesn’t match.
It keeps an audit trail of every match it makes through automated matching logic.
How deep that automation goes, and how much of the process it actually covers, is where tools start to differ. That’s what the criteria below are for.
For the fuller picture of how reconciliation fits into close and reporting, see what is financial close software.
How to choose reconciliation software: 7 criteria that matter
Seven criteria separate a reconciliation tool that scales with your business from one you’ll outgrow within a year.
1. Automation depth (rules-based vs. AI-driven matching)
AI can genuinely help match your transactions, that part isn’t controversial.
Whether it should decide, unsupervised, what counts as reconciled every time the process runs is the real question, and the answer depends on how much risk you’re willing to accept without a clear trail back to why a match happened.
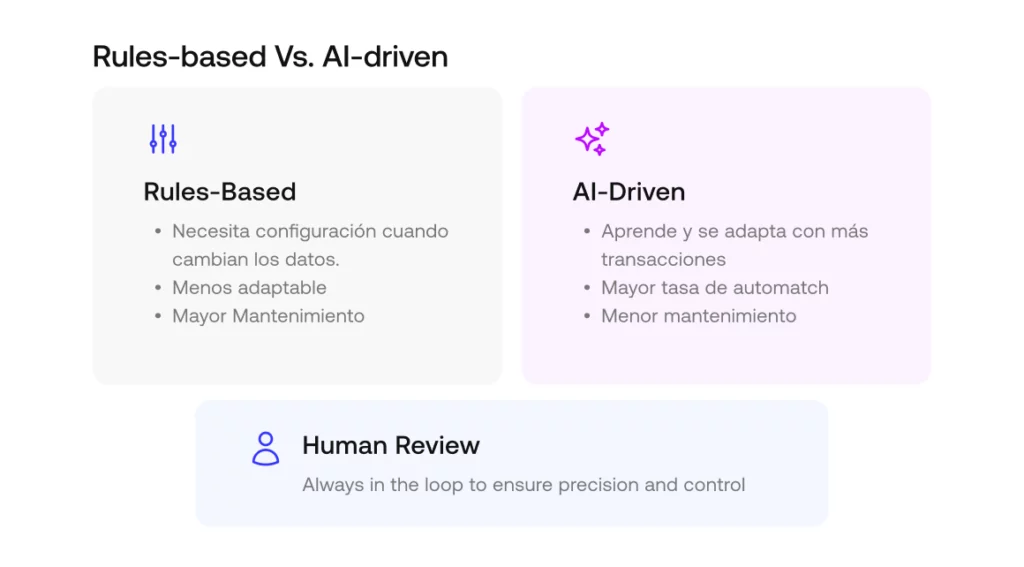
Some reconciliation automation relies on fixed rules that need to be reconfigured every time your data changes; other tools use AI or agentic matching that adapts as it processes more transactions.
Ask any vendor for their actual auto-match rate on data that looks like yours, not a generic benchmark, and ask what happens to the matches it can’t resolve on its own.
2. Transaction-level vs. trial-balance reconciliation
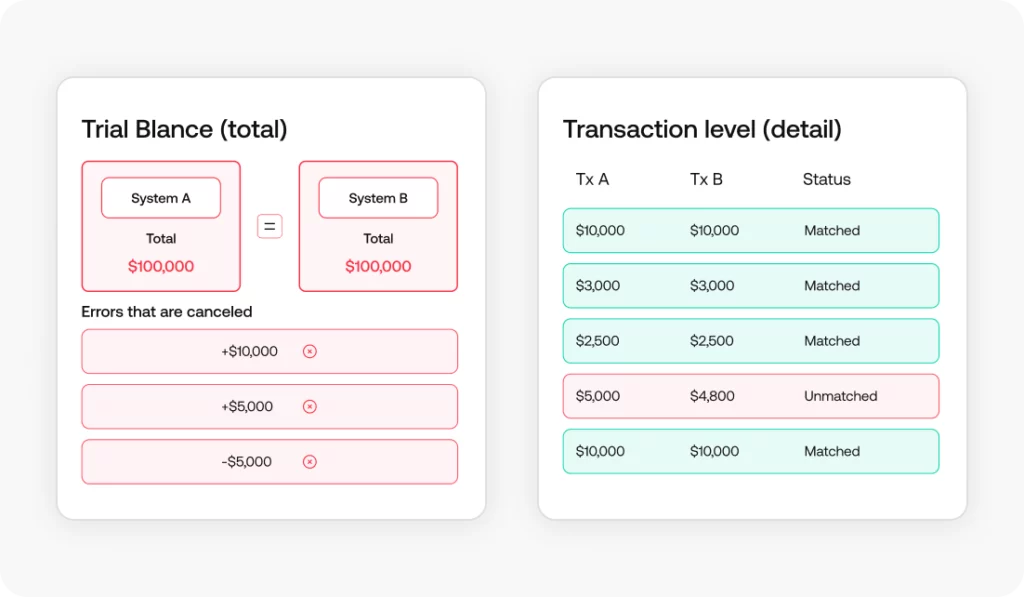
Two totals can match perfectly while the details underneath are wrong in ways that cancel each other out. That’s the risk with trial-balance reconciliation, which only confirms that summary balances agree.
Transaction-level reconciliation matches every individual transaction, so a discrepancy can be traced back to its source instead of just flagged as “off.” If your team needs to investigate differences rather than just confirm totals, this is one of the more consequential criteria on this list.
3. Data sources and ERP integration
A reconciliation tool is only as good as what it can actually see.
Check how many of your real data sources it connects to natively, from payment processors and banks to payment gateways and ERPs, and how.
No-code connectors and open APIs for ERP integration mean faster setup and less dependence on engineering time later. Ask what happens with a source that isn’t natively supported: is it a custom build, a manual workaround, or out of scope entirely?
4. Exception management and controls
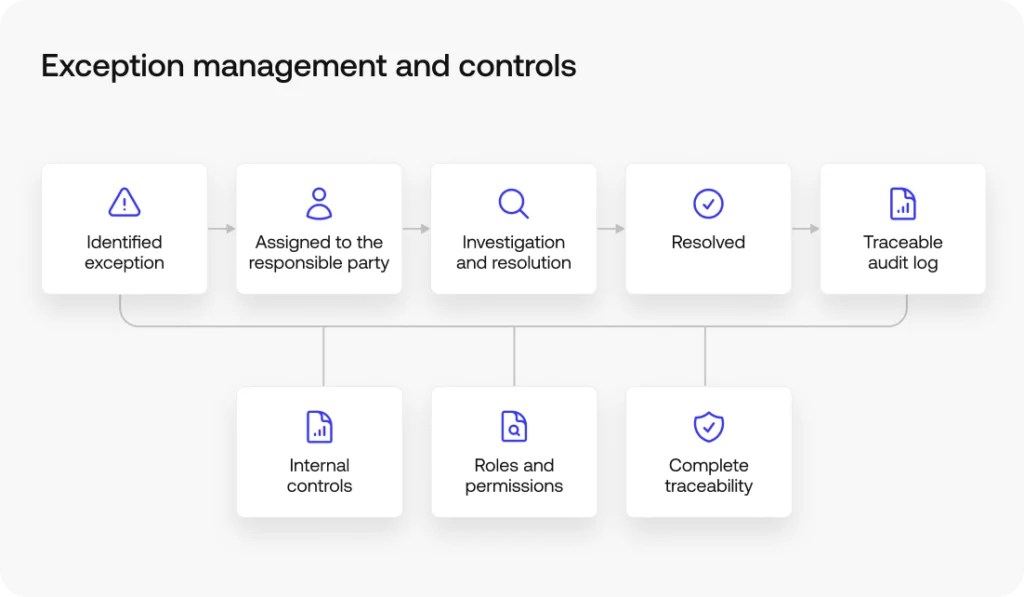
Reconciliation software should support exception management by routing exceptions to the right person, tracking how they’re resolved, and reinforcing internal controls like segregation of duties.
A static list of unmatched items that nobody owns doesn’t count as exception management.
Ask how exceptions are identified, whether resolution steps are logged, and how access is controlled by role.
5. Scalability for transaction volume
The tool that impressed everyone in the demo was tested on your current volume.
Ask what happens at two or three times that, because that’s the volume you’ll actually be running in a couple of years and scalability problems tend to surface quietly, as manual workarounds nobody planned for.
6. Security and audit-readiness
Look for role-based access, an immutable audit trail, and relevant security certifications, then push vendors to prove it rather than take their word for it.
Sample audit trails, certification documentation, and access control settings are all fair to request during evaluation.
7. Implementation time and ROI
“Go live in days” sounds great in a pitch deck and rarely survives contact with your actual data sources. Time-to-value depends on how many sources you’re connecting and whether implementation requires engineering support.
Ask for a realistic estimate based on your specific sources, then weigh ROI against that date rather than the one you saw in the demo.
A reconciliation software evaluation checklist
Use this reconciliation software comparison checklist to evaluate vendors side by side:
Auto-match rate has been tested against data similar to yours, a vendor’s generic benchmark doesn’t count
The tool supports transaction-level drill-down, beyond simple balance-level checks
It connects natively to your actual data sources (processors, banks, ERPs)
Exceptions are routed, tracked, and resolved with a visible audit trail
Performance holds up at 2-3x your current transaction volume
Security certifications and audit trail exports are available on request
You have a realistic time-to-value estimate tied to your specific data sources
Build vs. buy: when to build reconciliation in-house
For a lot of finance teams, building reconciliation in-house was never really a decision, it’s just what happened, usually in a spreadsheet, when volume was low enough that nobody minded.
The cost shows up later: maintenance falls on whoever built it (often IT, not finance), there’s little to no audit trail, and the process doesn’t scale without adding headcount.
That doesn’t make buying automatically right for every team, it depends on your volume, your data complexity, and how much internal engineering time you’re willing to spend maintaining a homegrown process.
The point of asking the question explicitly, instead of defaulting to whatever you already have, is making sure the decision matches where the business is headed, not just where it is today.
See how Simetrik handles reconciliation at scale: Request a demo.
Questions to ask a reconciliation software vendor
Use these questions to get past the demo script:
Matching & coverage
What’s your auto-match rate on data structured like ours?
Can we drill down from a summary match to the individual transaction level?
Which of our specific data sources do you connect to natively, and which require custom work?
Do you use AI or machine learning in your matching logic? If so, how does it interact with deterministic controls and what happens to the audit trail when the model changes?
Exceptions & audit
How are exceptions routed, and how are they resolved and logged?
If a discrepancy surfaces during an audit, how does root-cause investigation work end to end, and who owns it?
What security certifications do you hold, and can we see a sample audit trail?
Integration & architecture
Can we connect via API or webhooks for real-time processing, not just batch file uploads?
Implementation & support
What’s a realistic implementation timeline given our data sources?
What ongoing support is included after go-live?
How often do you release rule or platform updates, and does that require re-testing on our side?
Cost
How does pricing scale with transaction volume?
Red flags when comparing reconciliation software
Not every red flag shows up in a feature comparison. Watch for:
The tool only reconciles at the balance level, with no way to drill into transactions
Any configuration change requires submitting a ticket to IT
Audit trails exist but can’t be exported or reviewed independently
Performance or accuracy drops noticeably as data volume increases
Demos are run only on clean, “toy” datasets rather than data resembling yours
Matching is entirely AI-driven, with no deterministic layer and no explainable audit trail.
Matching the software to your team and industry
There’s no universal answer to which criteria matter most, it depends on who’s using the reconciliation software.
A finance operations team processing high volumes from multiple payment processors will likely weigh automation depth and data source coverage heaviest.
An accounting team focused on month-end close may care more about exception management and audit-readiness.
Industry shifts the picture too: payment service providers and banks both need reconciliation that holds up across processors, acquirers, and bank statements, while retailers reconcile different types of transactions at different volumes, which changes which criteria carry the most weight in practice.
Frequently asked questions
What is the best reconciliation software?
There’s no single best tool.
The right one depends on your transaction volume, data sources, and whether you need transaction-level matching or just balance-level checks.
Use a criteria checklist rather than a generic ranking.
Pricing usually scales with transaction volume, data sources, and use cases rather than a flat license, so compare on total value and time-to-value, not just sticker price.
Once you have your own criteria and a shortlist of vendors, the best next step is seeing how a platform performs against your actual data, not a demo script.
Simetrik’s reconciliation software is built around exactly that test. Request a demo to see it against your own data.
A sportsbook or online casino never closes. While one player deposits funds to bet on a game starting in minutes, another requests a withdrawal of their winnings. At the same time, a gateway processes transactions, applies fees, and settles payments. Everything happens simultaneously, across multiple providers, markets, and jurisdictions.
The challenge is not just volume, but variability. Each provider reports with different formats, identifiers, criteria, and timelines. References don’t always match across systems, and a minor change in a file can interrupt an entire control flow.
Every new gateway or jurisdiction adds a different logic to the operation. And in an industry where the business depends on verifying every deposit, withdrawal, fee, or in-game purchase, any discrepancy can translate into losses, cash errors, or regulatory exposure.
Without continuous, transaction-level reconciliation, two critical capabilities break down: real visibility into cash flow and traceability of outstanding items.
The blind spot in the cash position
Knowing how much capital is actually available, by provider and by region, is the foundation for sound financial and operational decisions.
The blind spot emerges because every movement crosses different systems. The same transaction may be recorded in the internal core system, at the payment provider, and at the bank with different identifiers, dates, or criteria.
When control is performed at an aggregate level, it becomes difficult to trace the gap between what the platform recorded, what the provider confirmed, and what actually landed in the bank account.
Withdrawals follow a similar pattern: they may be approved, in processing, executed, or confirmed to the player. Without a transaction-level view, it is not always possible to know which stage they are at or which items remain outstanding.
If reconciliation is only run in batches or at month-end close, the cash position stops being a verified figure and becomes an estimate. And that is not enough to define working capital, calculate immediate obligations, or demonstrate operational solvency to a regulator.
When outstanding items have no context or owner
The second breakdown is less visible, but can be just as costly.
It is not enough to detect that a transaction did not reconcile. You also need to know which one it is, how long it has been outstanding, at what stage it stalled, and who is responsible for resolving it.
Without that information, each item remains an open exposure: a duplicated credit, a missing transaction, a delayed settlement, an incorrect fee, or a discrepancy against the provider’s report.
When these cases are managed across spreadsheets, emails, or scattered exchanges, the team may identify the discrepancy without having the elements needed to close it. Many are only detected during the monthly reconciliation, by which point reconstructing the transaction, filing a claim with the provider, or correcting the record is far more difficult.
That is why reconciliation does not end when an anomaly is identified. Control must also encompass its investigation, assignment, and resolution.
Continuous, transaction-level, evidence-based control
Recovering visibility over cash and traceability over outstanding items demands more than aggregating reports or dashboards. It requires a scheme of continuous, transaction-level reconciliation, in which every position can be explained and backed by evidence.
Simetrik’s solutions make it possible to follow the complete journey of money: from when a transaction is initiated through to its settlement, accounting entry, and, if a discrepancy arises, its investigation and resolution. This is achieved through Domains: control modules designed to cover specific layers of the operation.
Some of the most relevant for the sector are:
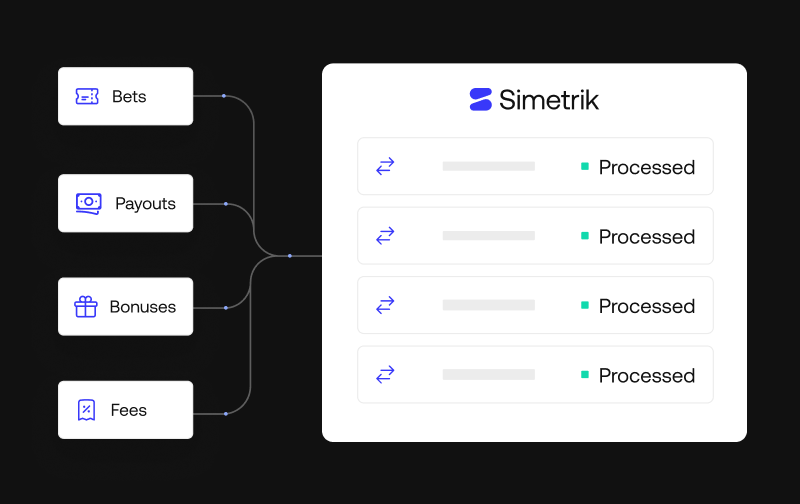
Cash In and Cash Out validate every inflow and outflow against internal operational data, payment provider information, and, where applicable, the bank movement. This allows deposits, withdrawals, and disbursements to be tracked from origin to settlement or confirmation, and identifies duplicates, missing transactions, rejections, incorrect amounts, or movements that have not yet completed their journey. Together, both Domains enable a verifiable view of cash flow: how much money is actually available, which provider holds it, and which items remain outstanding.
Fees & Billing controls the fees and charges applied by any payment provider, operator, or third party involved in settlement. Rather than assuming an invoice is correct, it cross-checks the charges applied against the agreed conditions and the transactions that originated them. In an industry where margin depends on multiple billing schemes, this control detects variances that might otherwise remain hidden within aggregate figures.
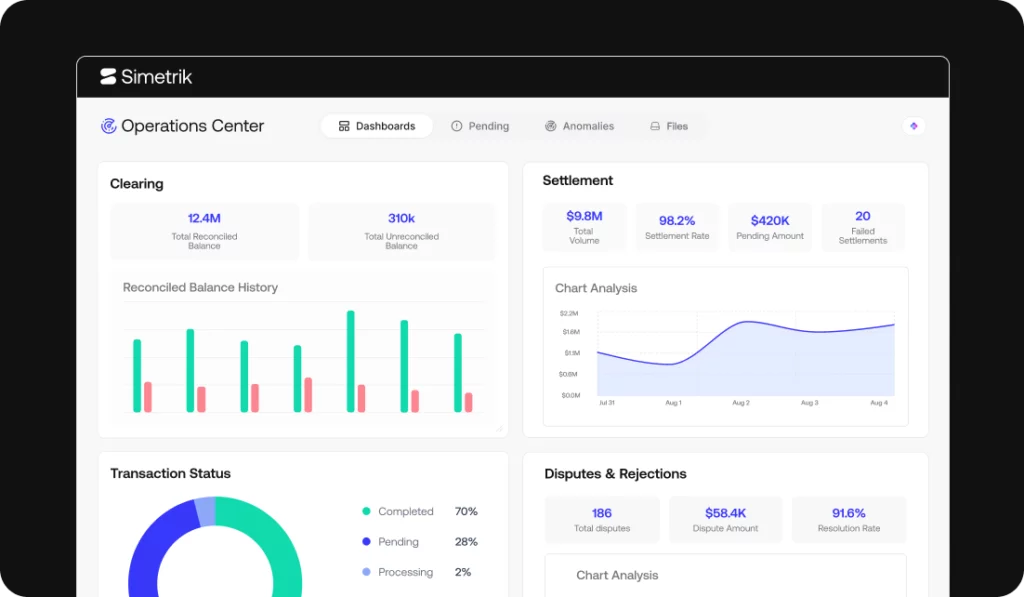
Unified Oversight & Alerts integrates these controls into a single view. It enables review of cash positions, distinguishes reconciled from unreconciled items, and tracks each outstanding item by status and owner. Control does not end when an alert fires. Simetrik also retains the evidence of what happened next: how the discrepancy was investigated, who was involved, and how it was resolved.
Simetrik has eight control Domains in total, adaptable to each operation’s structure and providers.
Two major players in Latin America have implemented Simetrik and demonstrate how this model works in practice.
BetWarrior: end-to-end financial control across four regions
BetWarrior operates a sports betting and entertainment platform in Argentina, Peru, Brazil, and other Latin American markets. With regional expansion, each gateway functioned as a separate universe: teams combined reports, resolved inconsistencies, and maintained increasingly complex manual controls.
With Simetrik, BetWarrior consolidated its six PSPs across each of the four regions where it operates, automated deposit and withdrawal reconciliation, and gained provider-level visibility with near real-time monitoring. Every movement can be tracked from origin to settlement, without relying on manual reviews or batch consolidations. Undefined statuses and inconsistent classifications are detected before they become losses.
Bplay: available cash and traceable outstanding items by provider
Bplay, Boldt’s sports betting and online casino platform, operates in Argentina, Paraguay, and Brazil. It processes deposits, withdrawals, and settlements through different gateways, each with its own formats, rules, and timelines.
This fragmentation made it difficult to centralize movements, validate fees, and control settlements. In addition, journal entries to SAP were generated manually, increasing operational workload and the risk of errors.
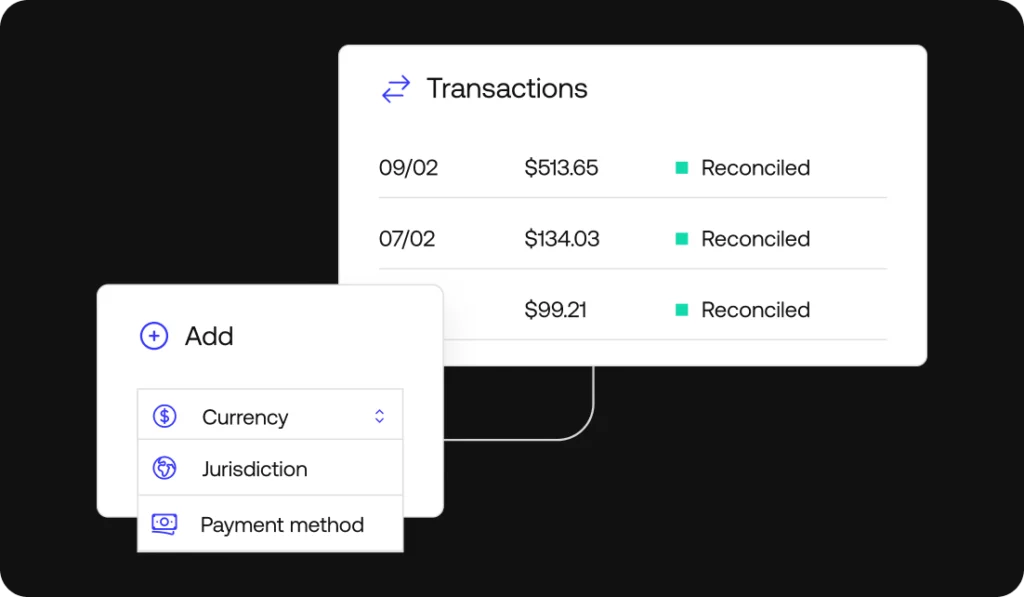
With Simetrik, Bplay automated 1:1 reconciliation across its five gateways, validating fees and agreed timelines per transaction. In a single view, teams can consult the available cash by provider and the status of each discrepancy.
The model also automatically generates 20 types of journal entries to SAP, reducing the manual workload at month-end close.
BetWarrior and Bplay started from different operations, but faced the same problem: isolated gateways, late discrepancies, and cash positions based on unvalidated information.
Continuous control makes it possible to move from aggregate totals and after-the-fact reviews to a model where every movement can be explained, every discrepancy managed, and every financial position backed by transactional evidence. This is how Simetrik works for the Betting & iGaming industry.
The difference is concrete: operating with verified data or making decisions based on estimates that are only corrected at month-end close.
In an industry where money never stops moving, control cannot either.
Request a personalized demo and discover how Simetrik can bring greater visibility, traceability, and control to your financial operation.
Imagine an agent analyzing thousands of unreconciled transactions, identifying a pattern, and designing a new matching rule. Before implementing it, it reviews the data sources involved, evaluates its impact, and determines which tools it needs to execute the change.
If the action falls within the permissions and criteria defined by the organization, it can proceed autonomously.
If it recognizes that a decision requires additional validation, it brings in the right person. Once the logic is established, the rule is applied consistently across millions of records.
That scenario reflects one of the main opportunities for applying AI in financial operations: building agents capable not only of understanding what the user needs, but also of carrying out the right action with the level of precision, traceability, and control each case demands.
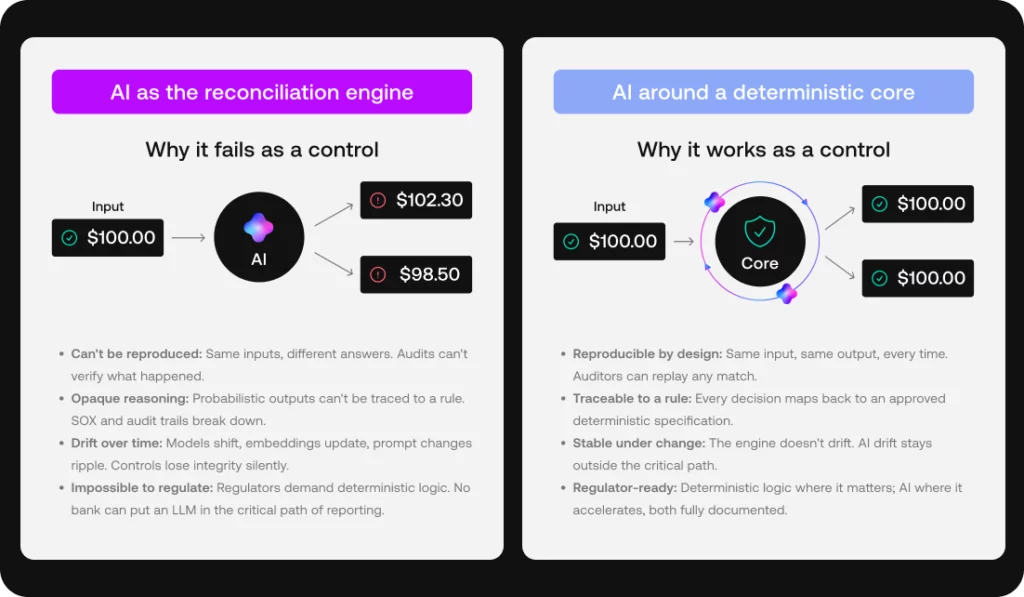
It also reflects the logic behind Simetrik Agent: an autonomous agent that can operate financial control end-to-end and knows when to reason probabilistically, when to rely on deterministic tools, and when to bring in a person.
To achieve this, these agents combine different capabilities:
Probabilistic models allow them to interpret context, detect patterns, and find solutions.
Deterministic tools, on the other hand, ensure that actions requiring precision, reproducibility, and auditability always follow a defined logic.
The sophistication lies not in choosing one capability over the other, but in the agent knowing when to use each one, how to combine them, and at what point to incorporate human intervention.
One Agent, Different Capabilities
AI models learn from patterns and interpret available information to generate a response based on context.
That flexibility allows them to:
understand requests in natural language;
recognize structures and relationships within data;
investigate anomalies and group exceptions;
suggest rules, transformations, or potential solutions;
adapt to scenarios that were not previously defined.
But that same probabilistic nature means a request can produce different responses even when the input, context, and instruction remain unchanged.
Deterministic tools provide a different capability: reproducible execution.
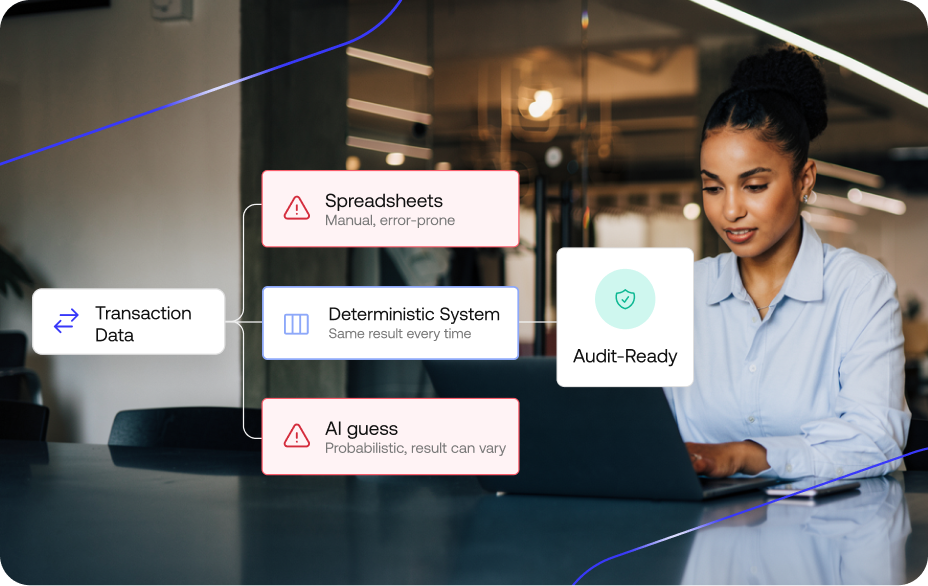
In a deterministic system, if a control receives the same input and the same configuration, it always returns the same result. It doesn’t need to reinterpret the intent with each execution: it applies the specification that governs the operation.
In financial control, an agent can interpret, investigate, and propose. But it cannot improvise where the business needs certainty.
This applies not only to reconciliation. It also covers journal entry generation, approval workflows, regulatory reporting, accounting reviews, and any instance where an organization needs to demonstrate how it arrived at a result.
That distinction is critical in auditable operations. To reconstruct what happened, knowing the result is not enough; it must also be possible to repeat exactly the logic that produced it.
In financial operations, both capabilities serve complementary functions: AI understands, investigates, configures, and decides; deterministic tools turn those decisions into stable, versioned, and traceable processes.
An agent prepared to operate in finance needs to combine both.
Autonomy Designed for Financial Operations
A financial agent doesn’t just need to reach an answer. It also needs to recognize what level of precision, traceability, and oversight each action requires.
When facing an exception, for example, it can analyze the context, find patterns, and propose a resolution. If it needs to apply a rule across millions of transactions, it can rely on a deterministic tool to ensure the logic is applied consistently.
The agent doesn’t lose autonomy by using specialized tools. On the contrary: it can turn its reasoning into real actions without giving up control over the operation.
The same applies to human intervention. In some cases, it can move end-to-end within established permissions. In others, it identifies that a decision requires a responsible party’s approval, presents the necessary context, and resumes the flow once validation is received.
Intervention doesn’t need to be present at every step. The key is that the agent recognizes when it is necessary.
This combination makes it possible to automate complex operations without turning them into a black box. Every action is recorded, configurations can be versioned, and results are linked to the logic that produced them.
How Simetrik Does It
Simetrik was built as an AI-native infrastructure for financial control. Its architecture allows AI to intervene throughout the operation and use different tools depending on the nature of each task.
During configuration and initial onboarding, it can recognize formats, link fields, generate transformations, recommend parsers, suggest rules, or assist in designing an accounting model.
This allows new controls to be implemented faster and reduces the manual work required to understand data sources, map data, and configure operations.
Once a logic is defined, Simetrik Agent can convert it into a deterministic specification and apply it across Simetrik’s infrastructure. When the task requires analysis or interpretation, it uses probabilistic capabilities. When it demands a stable, exact, and verifiable result, it relies on Simetrik’s deterministic core — made up of more than 110 financial control-specific functions.
Everything happens within the same permissions, governance, and audit model.
After execution, AI can also investigate exceptions, detect anomalies, group errors, search for possible causes, and recommend or implement resolutions.
The agent determines which capability to use at each moment. The organization retains visibility into what it did, which tools it used, and what the final result was.
Simetrik Agent: From Intent to Execution
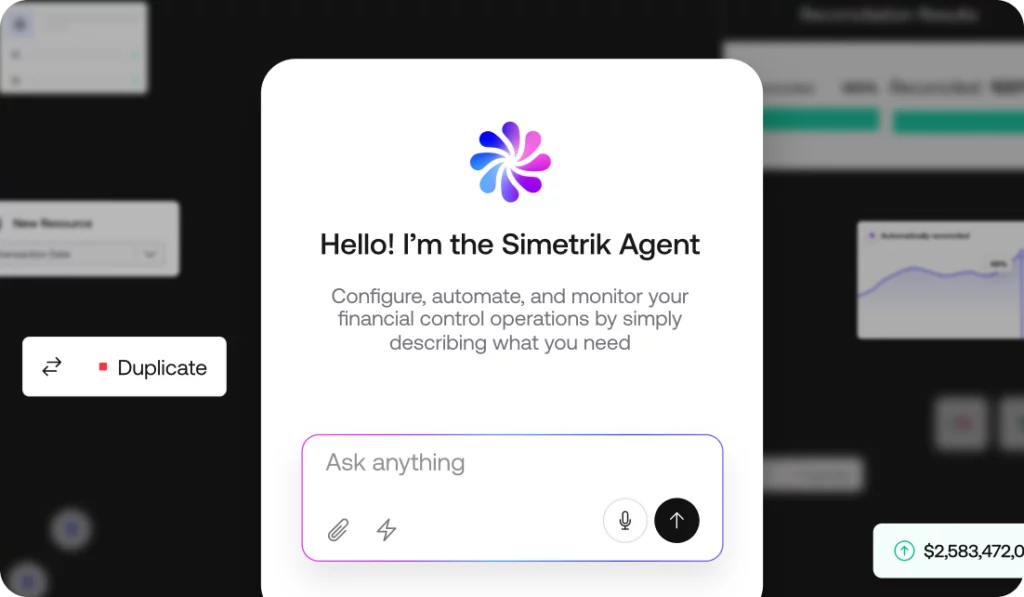
Simetrik Agent brings this architecture to a conversational experience within the platform.
It is equipped with the expertise and knowledge Simetrik has built alongside more than 180 clients globally, along with best practices specific to financial control, reconciliation, auditing, and exception handling.
Conversing with Simetrik Agent means accessing an expert that can support financial control 24 hours a day, 7 days a week.
The user can describe what they need, add files, and provide context. The agent interprets the intent, reviews the workspace, identifies the relevant data sources and dependencies, and defines the path forward.
It can design reconciliations, configure sources and transformations, create rules, schedule executions, investigate exceptions, and query results. It is not limited to explaining how to perform a task: it can act on the operation.
When the user enables it, Simetrik Agent can operate autonomously. Every action is carried out within Simetrik’s permissions model and is recorded.
It can also identify when a decision requires human intervention, present the relevant information in financial language, and incorporate the approval into the workflow without losing context.
An Open Box Agent
Autonomy does not mean losing visibility.
Simetrik Agent does not function as a black box, but as an open box: a system open to team oversight. Users can understand what it is doing, which data sources it consulted, what logic it is applying, and what actions it is taking.
Rather than receiving only a result, they can follow the process in terms understandable to someone working in finance: knowing which condition was met, which rule was used, which dependency was modified, or why an operation was sent for review.
Teams can also supervise the work, change configurations, adjust permissions, or intervene when they deem it necessary.
This capability turns the human into more than a mandatory approver at the end of a workflow. It allows them to define the level of autonomy, understand the agent’s decisions, and maintain control over the full operation.
The greater the system’s transparency, the greater the capacity to delegate with confidence.
MCP: Specialization for the Agents Teams Already Use
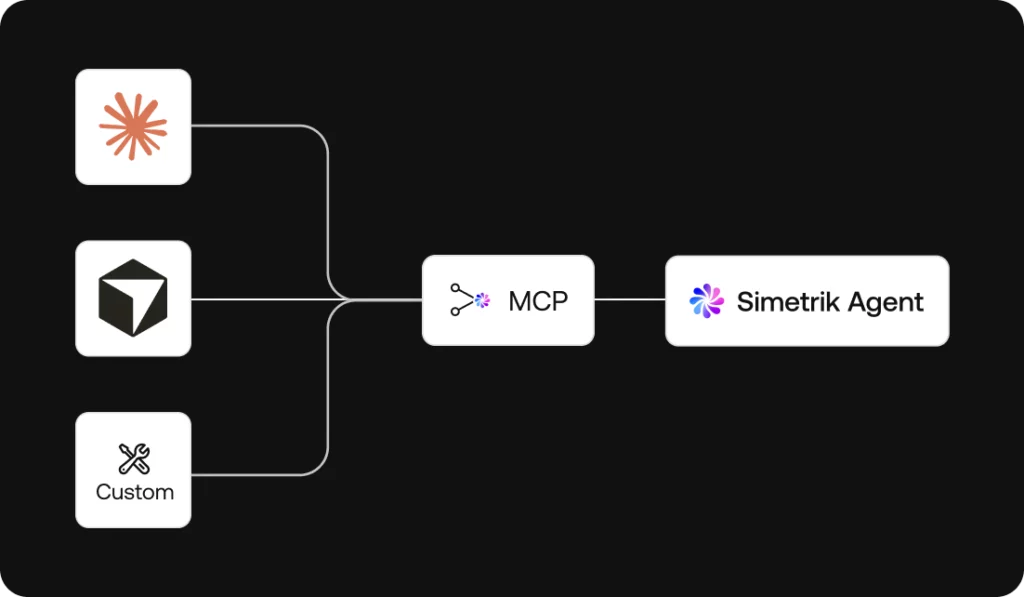
Many organizations already work with Claude, Copilot, Gemini, or internally developed agents. These systems can understand instructions and coordinate tasks, but they don’t automatically come with the knowledge and specific context of each financial operation.
Through MCP, these agents can connect with the financial knowledge and control capabilities of Simetrik Agent.
This means the user retains in their own agent the company context and the tools they already work with, and gains the capabilities, financial knowledge, and infrastructure available in Simetrik.
The team doesn’t need to switch environments to access information on data sources, controls, dependencies, financial logic, and exception handling.
Simetrik provides the domain specialization. The organization’s agent retains the broader business context.
This integration avoids the need for each company to rebuild from scratch the reconciliation logic, auditing practices, and infrastructure needed to operate real controls.
One Control, Different Ways to Operate It
Simetrik offers different ways to work on the same AI-native infrastructure.
Simetrik Agent is available within the web experience, integrated directly into the platform. MCP allows the agents each organization already uses to connect with Simetrik’s financial knowledge and control capabilities.
In all cases, AI operates on the same financial knowledge, the same engine, the same permissions, and the same traceability.
This is not about adding AI as an isolated layer on top of pre-existing processes. Simetrik was built from its foundational architecture so that agents, deterministic tools, and human teams can operate within the same system.
As agents gain capabilities, they will be able to take on an ever-larger share of the financial operation. Their true potential will depend not only on the volume of automated tasks, but on their ability to understand context, choose the right tools, act with precision, and bring in a person when appropriate.
That is the differentiator of an agent designed for the financial world: it doesn’t just reason and respond. It knows how to act.
Simetrik combines autonomy, specialized knowledge, governed execution, and human control in the same AI-native infrastructure. The result is a more powerful, transparent agent and ready to operate real financial processes.
If you’re evaluating alternatives to Simetrik, you already know what a reconciliation platform does. You’re likely weighing whether to build your own engine, stick to spreadsheets, or adopt newer AI tools promising “fully automated” exception resolution.
What does Simetrik do? Simetrik is a dedicated financial operations control platform that standardizes data, executes deterministic reconciliation rules, surfaces exceptions, and preserves an audit trail. Its AI layer assists configuration and analysis; it does not replace the governed matching engine or human accountability.
Here is the line every CFO needs to draw: A financial control must produce the exact same result every single time. While some newer AI tools promise to let autonomous agents close exceptions without human oversight, a probabilistic guess isn’t an accounting control, it’s an audit risk.
This guide breaks down where in-house builds, spreadsheets, and AI tools hold up, where they fail under audit scrutiny, and how to choose an architecture built for long-term compliance.
Comparing financial reconciliation alternatives at a glance
Alternative 1: Building a financial reconciliation tool in-house
For a lot of teams, the first real alternative to buying a platform isn’t another vendor. It’s the engineering team down the hall. If you already have developers who understand the payment flow, building a reconciliation tool internally can look like the obvious move: no procurement cycle, no new vendor relationship, full control over the roadmap.
What an in-house financial reconciliation build usually includes
A typical in-house reconciliation build covers a predictable set of pieces:
Ingestion from bank files
Processor APIs, or internal databases
An ETL layer or custom scripts to clean and standardize that data
Matching logic written specifically for your transaction types
Accounting rules encoded directly into the system or a connected tool
A way to generate files or journal entries for the ERP
Some version of monitoring, versioning, and an audit trail.
Not every build includes all of this from day one. Most start with ingestion and matching, then add the rest as gaps show up.
When a custom-built reconciliation system is the right call
Building internally is a legitimate decision, not a fallback you settle for. It makes sense when the case is genuinely simple: one or two data sources, stable transaction logic, low volume, and a technical team that already understands the flow end to end. In that situation, a custom build gives you something a vendor platform can’t: complete control over the release schedule and the exact logic, with no external dependency on someone else’s product roadmap.
Where in-house reconciliation software breaks down as transaction volume grows
The trouble tends to start later, not at launch. Every rule change needs an engineering ticket and a QA cycle, so finance ends up waiting on IT for things that should take minutes. The system’s continuity depends on the two or three people who understand how it actually works, and if they leave, the institutional knowledge goes with them.
Visibility stays limited for the finance team that has to use the output, because most in-house builds get optimized for the data pipeline, not for the person reviewing exceptions. Permissions, versioning, traceability, and alerting all have to be built by hand on top of the matching logic itself, which turns into its own project. And technical debt piles up quietly until the day you add a new entity, a new currency, or a new data source, and realize the system was never built to flex that way.
Alternative 2: Using general AI tools for financial reconciliation
Where AI Copilots and Chatbots Fit in a Reconciliation Workflow
General-purpose AI tools genuinely help with parts of this work. They’re good at interpreting messy files, suggesting field mappings, drafting or explaining formulas, and letting someone describe a rule in plain language instead of writing it from scratch. Used this way, they’re leverage: they take work off someone’s plate without taking over the decision.
Why financial reconciliation needs a reproducible control, not a probabilistic answer
Here’s where it gets more complicated. A chatbot or AI agent that decides, on its own, whether a transaction matches or how an exception gets closed is solving the wrong problem in an appealing way. A financial control needs to produce the same result from the same inputs every time. That’s what makes it something an auditor can rely on.
AI agents don’t actually reason, they output what is most statistically probable based on context. Where a deterministic system knows without a doubt that $1 + 1 = 2$, a probabilistic AI evaluates what usually follows “$1 + 1$.” That makes it prone to repeating common errors, and when context is missing, the margin for error spikes.
An output that changes on the same data isn’t a financial control; it’s a guess with good manners. True controls require absolute predictability. AI should assist with patterns and rules, but a deterministic engine must execute the logic, and a human must make the final call.
Alternative 3: Reconciling payments and transactions in Excel or Google Sheets
Why Excel and Google Sheets were the default starting point for reconciliation
Almost every finance team starts here, and there’s nothing wrong with that. Exporting statements from a bank or processor and cross-checking them in a spreadsheet, using VLOOKUPs, pivot tables, the occasional macro, is how most reconciliation processes begin before anyone formalizes them. At low volume, with a handful of sources, it works fine. It’s cheap, flexible, and everyone on the team already knows how to use it.
Where manual spreadsheet reconciliation stops scaling
The limits show up gradually, then all at once. Spreadsheets are intensive in time: every new statement means another round of exporting, formatting, and cross-checking by hand. They’re error-prone in ways that are hard to catch, because a broken formula or a mis-copied row doesn’t announce itself. There’s no real-time visibility into where the reconciliation stands, and no reliable record of who changed what, when, or why, which becomes a real problem the first time an auditor asks.
None of this makes spreadsheets a bad choice early on. It just means the same tool that worked fine at 500 transactions a month starts working against you at 50,000.
A framework for evaluating reconciliation software alternatives
Whatever you’re comparing, an internal build, a spreadsheet, an AI tool, or a vendor platform, the same four questions tend to separate what actually works from what just looks good in a demo.
Questions to ask about traceability and audit trail
Can the system reconstruct exactly what happened for any given match or exception? Not just that it matched, but which rule fired, what data it used, and why it reached that result. If you can’t answer that six months later, you don’t have a control. You have an output.
Questions to ask about who owns exception resolution
When something doesn’t reconcile, who takes the final action, and can that action be explained afterward? The honest answer matters more than whether the system “resolved” something on its own. A flagged exception that a person reviewed and closed is more defensible than an automated fix nobody double-checked.
Questions to ask about configuration flexibility
What happens the first time a case doesn’t fit the standard pattern? Does the team wait on a new setup, or can they describe the rule and adjust it directly? Some platforms lean on natural-language interaction for exactly this. Simetrik Agent, for instance, lets a team describe a workflow instead of relying only on a fixed template. A tool that adapts to the edge case is worth more than one that only handles the common one.
Questions to ask about maintenance cost and scalability
Does your current infrastructure actually support your expected growth and compliance requirements across the short, medium, and long term? More specifically, what does it cost, in time, engineering tickets, and lost institutional knowledge, to keep it running as sources, currencies, entities, or rules change?
This question applies just as much to a spreadsheet model or an internal build as it does to any vendor platform, and it’s usually the one that gets skipped until it’s too late.
When a dedicated reconciliation control platform is worth the switch
There’s a point where each of the alternatives above stops being enough, and it’s rarely a single event. It’s an accumulation: new data sources show up, entities and currencies multiply, and exception volume starts growing faster than the team reviewing it. At the same time, constant variability in statements and documents forces teams to reconfigure their manual setups or re-engineer their code with every slight format change. Control requirements from finance, audit, or a regulator start asking for things the current setup was never built to provide.
That’s the point where a platform built specifically for transaction-level control starts to earn its cost. Simetrik connects the pieces that a build or a spreadsheet usually keep separate: data preparation, matching, exception handling, and the path into accounting, under one system that business teams can configure directly, without opening an engineering ticket for every change.
The core that executes the matching logic is deterministic, so the result stays reproducible. The AI layer around it assists with configuration, pattern detection, and natural-language interaction, without taking over the final decision.
See how Simetrik’s control platform fits into a reconciliation operation that has already outgrown a spreadsheet or an internal build.
How Simetrik handles reconciliation, from matching to audit trail
The architecture behind Simetrik’s deterministic matching engine
Simetrik ingests transaction data from banks, processors, and internal systems, prepares it into a consistent structure, and applies configured rules to match records against each other. The engine that executes those rules is deterministic: the same data and the same configuration produce a consistent result. Around that core sits an AI layer that assists the process. It can suggest matching logic, identify fields, help build transformations, and support conversational configuration through Simetrik Agent, but it doesn’t replace the rule that actually executes. That split matters because a financial control has to be reproducible: a result a team can trace back to a specific rule is one they can defend to an auditor, and a result that came from a model’s best guess isn’t.
How Simetrik detects and resolves reconciliation exceptions
When a transaction doesn’t match cleanly, Simetrik flags it and routes it with context: which rule ran, what data it compared, and why it didn’t clear. A finance team reviews that exception and takes the resolving action from there. Automating the detection, the context, and the routing while leaving the final decision to a person is a deliberate design choice, not a shortcut. A financial exception closed without a documented, reviewable reason is a bigger risk than one that took a person a little longer to confirm.
Simetrik’s audit trail and security certifications
Simetrik’s security program includes ISO/IEC 27001, ISO/IEC 27701, ISO/IEC 27018, SOC 1 Type 2, SOC 2 Type 2, SOC 3, and PCI DSS. Matches, exceptions, and rule applications can be traced back to the configuration that produced them, and the workflows that connect reconciliation to accounting carry that same traceability into journal entries and the reports a team may need for an audit. Certifications are a floor, not the differentiator. What matters more day to day is whether a team can reconstruct exactly what happened, for a given transaction, months after the fact.
Frequently asked questions about Simetrik alternatives
Is Excel or Google Sheets a viable long-term alternative to reconciliation software?
No. Excel and Google Sheets are a viable starting point, not a long-term answer, once volume or complexity outgrows what a team can check by hand. Spreadsheets lack traceability, real-time visibility, and a record of who changed what, which becomes the actual cost as transaction volume rises.
Can general AI tools, like a chatbot or AI agent, replace a reconciliation platform?
General AI tools excel at auxiliary tasks like interpreting messy files, suggesting field mappings, or drafting formulas, but they shouldn’t execute control decisions autonomously. Reconciliation outputs directly drive executive decision-making, tax filings, and financial reporting. Because general AI operates on probability rather than deterministic rules, a non-reproducible answer directly undermines data confidence and credibility. Replacing strict controls with statistical guesses can expose a team to misinformed decisions, audit findings, and regulatory risk, defeating the purpose of a financial control.
Does a reconciliation platform need to execute the fix automatically, or is flagging enough?
A modern platform should support deterministic auto-matching, governed human intervention for complex exceptions, and assisted remediation workflows. What matters is applying the right level of control to each case. Known patterns can be resolved through configured rules, while sensitive edge cases are routed with full context for review and approval. A unified audit trail preserves efficiency without sacrificing reproducibility.
When does it make sense to move from a spreadsheet or internal tool to a dedicated platform?
The switch becomes necessary when you hit limits on both scalability and reliability. Scalability breaks down as growing data, entities, and currencies require unsustainable headcount or dev tickets. Reliability breaks down because spreadsheets can’t track user actions or prove data integrity. When a spreadsheet claims an operation is “90% reconciled,” it can’t answer: Who verified this? Under what rules? Has it been modified? When you can no longer prove how your numbers were reached, the audit risk far outweighs the cost of a dedicated platform.
Does configuration flexibility matter more than a library of pre-built templates?
What matters is whether an approach can adapt to a workflow that falls outside standard patterns without stalling on new setup work, through natural-language interaction, assisted rule-building, or both. A large template library speeds up standard cases. Genuine configuration flexibility is what handles the case that doesn’t fit one.
Should certifications or pricing structure decide which reconciliation option is right for you?
They’re worth checking, but they answer a narrower question than the one that actually matters: can this approach reconstruct what happened, who owns the fix, and what it costs to maintain as your operation changes. Certifications and pricing models are inputs to that decision, not a substitute for it.
Does Simetrik use AI for reconciliation matching?
Yes. Simetrik pairs a deterministic core that executes configured matching rules with an AI layer that assists configuration, suggesting matching logic, identifying fields, and supporting natural-language interaction through Simetrik Agent.
Does Simetrik resolve reconciliation exceptions automatically?
Simetrik detects discrepancies as data is processed and routes them with context so a finance team can review and take the resolving action. That’s a deliberate design choice, not a limitation: a result a person can trace, explain, and defend to an auditor is worth more than one an automated process applied without review.