Category: Payments

The cash reconciliation process, step by step

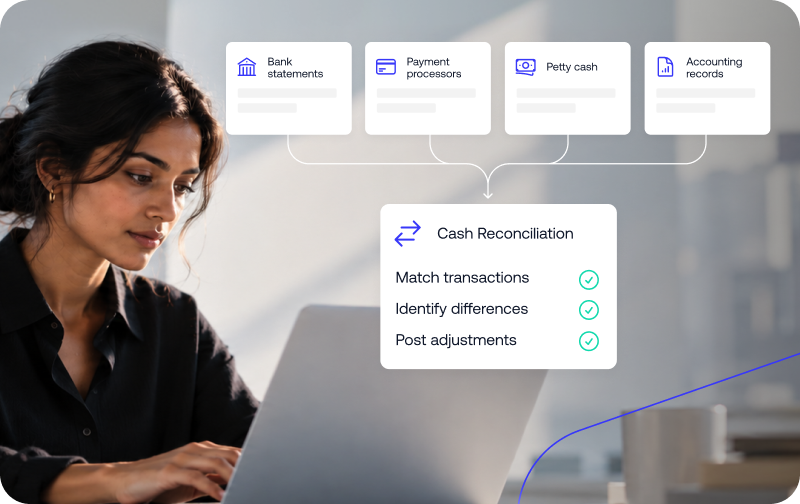
The cash reconciliation process compares what your accounting records say you have in cash against what your bank statements, payment processors, and petty cash counts actually show. Run through it consistently and discrepancies get caught in days, not discovered months later during an audit.

Knowing how to do cash reconciliation comes down to running the same set of checks every cycle, on a fixed schedule rather than as a reaction to something looking off. This guide walks through how to reconcile cash across every source you handle, from bank accounts to petty cash to processor payouts, in six steps you can repeat on a schedule.

What the cash reconciliation process actually compares

The process crosses three layers: the accounting records or internal records your team maintains in the accounting system, the general ledger where those movements get consolidated, and the external evidence, bank statement, payment processors, cash on hand, that confirms whether what was recorded actually happened.

Why the cash reconciliation process matters for cash flow and financial integrity

Without this process, cash flow management rests on figures nobody verified against the source. That distorts financial reporting and financial statements, weakens the financial integrity and financial accuracy that treasury operations depend on, and leaves the balance sheet showing a cash position that may not actually exist.

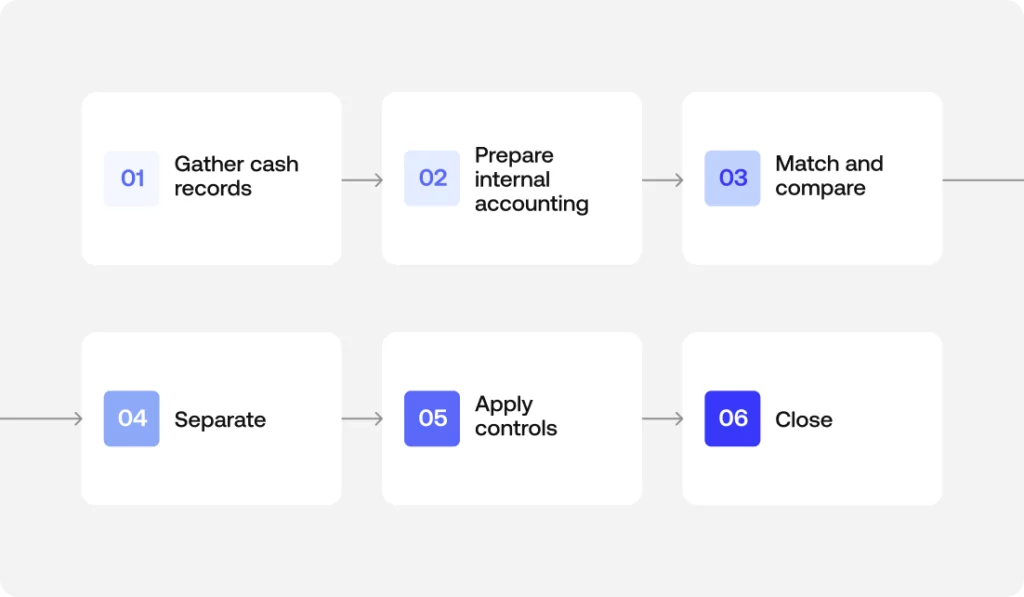
The cash reconciliation process in 6 steps
cash reconciliation process

Step 1: Gather cash records from every source

Pull the bank statement from every account, the reports from payment processors, the cash on hand count if you handle petty cash or cash registers, and the detail of customer payments and withdrawals for the period.

Simetrik can ingest financial and operational data from banks, processors, and other compatible sources, preparing it for a reconciliation workflow.

Step 2: Prepare your internal accounting records

Before comparing anything, your accounting records or internal records, what the accounting system says happened, need to be complete: all cash inflows and withdrawals from the period, with nothing left unrecorded.

Step 3: Match transactions and compare balances

This is where transaction matching happens: crossing each movement against its counterpart to compare balances, checking the calculated ending balance against the bank balance and the cash balances reported by each source.

Simetrik’s reconciliation engine applies configured rules to compare records and separate matches from the exceptions that need investigation, with data preparation capabilities, source unions, date format normalization, before the matching runs.

Step 4: Separate timing differences and unrecorded transactions from real errors

Timing differences, deposits in transit, outstanding checks, resolve on their own in the next cycle. Unrecorded transactions (something that happened but nobody logged) and data entry errors need active correction. Unauthorized transactions and unexpected bank fees fall into the same review.

A $2,000 deposit recorded in the books but not yet showing on the bank statement is a timing difference. That same amount with no internal record at all is an unrecorded transaction, and it needs to be traced back to its source.

Step 5: Apply controls and flag anything unusual

Segregation of duties, making sure the person reconciling isn’t the person approving, is the most basic internal control here. Documenting every adjustment supports the audit trail and answers to regulatory requirements and regulatory compliance, even though reconciliation on its own isn’t a fraud prevention tool. The error detection that happens in this step is what functions, in practice, as early fraud detection.

Simetrik’s product materials describe approval flows with maker-checker separation for manual adjustments, along with a traceable audit trail over the rules, actions, and results of a reconciliation.

Step 6: Post adjusting entries and close

Every real difference becomes journal entries or adjusting entries reflected on the balance sheet. With cash reconciled, forecasting and treasury planning start from a reliable number instead of an estimate built on unverified data.

How Simetrik’s Cash In domain reconciles inbound cash

Every step above applies differently depending on which side of cash movement you’re reconciling. On the inflow side, that means confirming that customer payments, payment processor settlements, and deposits actually landed as recorded, before revenue gets booked against money that hasn’t cleared, the core of managing cash inflows well.

Simetrik’s Cash In domain reconciles collections across processors, acquirers, and bank statements on a continuous basis, rather than only at the point of deposit.

Cash Out and Simetrik’s control over outbound payments

The outflow side works the same way in reverse: every payout, withdrawal, or disbursement needs to be traced from the instruction that authorized it to the bank confirmation that it actually went out, with no duplicates and nothing sent to the wrong account, whatever mix of payouts, withdrawals, and disbursements make up your cash outflows.

Simetrik’s Cash Out domain applies the same logic, validating outbound payments from instruction through to bank confirmation.

Cash reconciliation vs. bank reconciliation and account reconciliation

Bank reconciliation is one source within the cash reconciliation process, specifically, crossing the bank against the books. Account reconciliation is the broader category still: it covers cash, but also accounts receivable, accounts payable, and any other account on the balance sheet. Cash reconciliation sits in the middle, more specific than account reconciliation, broader than bank reconciliation alone.

Manual cash reconciliation vs. automation

Manual data entry works when volume is low and sources are few. As accounts, currencies, or daily transaction counts grow, keeping the 6 steps running by hand becomes the bottleneck, since reviewing line by line stops scaling no matter how good the judgment behind it is. That’s exactly where cash reconciliation automation changes the equation.

Within its Cash In domain, Simetrik can compare expected movement against the records of the systems and participants involved, identify differences, and maintain a traceable view of status, the same kind of high-volume comparison that steps 1 through 4 of this article describe doing by hand.

Cash reconciliation process FAQs

What are the steps in the cash reconciliation process?

At a minimum: gather records from every cash source, prepare your internal accounting records, match transactions and compare balances, investigate discrepancies, apply controls, and post adjusting entries. The order matters more than the exact number of steps a given team uses.

What is a cash reconciliation form?

It’s a template, paper or digital, used to document the comparison: the recorded balance, the actual balance from source documents, each reconciling item, and a sign-off from whoever reviewed it. It’s the evidence trail, not the reconciliation itself.

What is a cash reconciliation statement?

It’s the finished output of the process: a document showing the starting balance, every adjustment that explains the difference, and the final adjusted balance that both the accounting records and the source documents agree on.

How often should the cash reconciliation process run?

Daily for high-volume cash operations, retail, payment processing, multi-location businesses. Monthly, tied to the close, is the minimum for lower-volume operations. The right cadence depends on how fast unresolved discrepancies would otherwise pile up.

What causes discrepancies in the cash reconciliation process?

Most are timing differences that resolve on their own. The ones that don’t are usually data entry errors, unrecorded transactions, unexpected bank fees, or occasionally an unauthorized transaction that needs investigating right away rather than waiting for the next cycle.

Next step: Run this process on connected, rules-based data

The cash reconciliation process works the same by hand as it does with cash reconciliation automation running underneath it, the difference is how much of the daily matching holds up on its own, without someone reviewing it transaction by transaction. You can compare expected movement against connected records.
Request a demo

Simetrik for TSYS Clients: Reconciling Acquiring Data at Scale

Acquiring banks, ISOs and merchant portfolios depend on TSYS to process card payments. TSYS handles authorization, and clearing, and it reports on the activity it processes. But confirming that the processed activity matches what lands in your bank accounts and general ledger is a separate job. For many finance teams, that job still runs on manual checks, copy-pasted totals and spreadsheets.

Simetrik is built for that gap. TSYS processes the transactions. Simetrik helps TSYS clients verify that the data TSYS produces matches their deposits and their books, down to the transaction.

This guide explains why TSYS acquiring data can be difficult to work with and what the manual process looks like today. It also covers how Simetrik turns raw TSYS output into automated, auditable financial checks.

The challenge of managing TSYS acquiring data

On the acquiring side, TSYS processes card transactions for merchants on behalf of acquiring banks and ISOs. It routes authorizations, submits transactions to the card networks for clearing, and calculates interchange and processing fees. It also funds merchants through settlement deposits.

Every step leaves a data trail. Finance teams have to reconcile several things:

  • authorizations and cleared transactions, which often land on different days;
  • settlement batches and the net deposits that reach the bank;
  • interchange, network assessments and processing fees, which are usually netted out of the deposit instead of shown line by line;
  • chargebacks, reversals and adjustments, which can change settled amounts after the fact.

None of this is a flaw in TSYS. It’s how card acquiring works. But it creates exactly the kind of multi-source, transaction-level matching that manual processes struggle with as merchant volume grows.

The manual reality: from green screens to unstructured data

Green screens as the daily system of record

Many TSYS environments still rely on legacy host-based systems accessed through 3270-style terminal screens, informally called “green screens.” Analysts log in, navigate across multiple screens, and copy-paste values into daily balancing spreadsheets. Each screen has its own format and its own tables.

Several of the reports teams depend on are only available inside these screens and don’t feed into any BI tool. The screens also have no export function, so every number that reaches a spreadsheet is typed or pasted by hand.

This makes TSYS reconciliation a variability problem as much as a volume problem. The effort comes from how many formats a team has to pull together each day, not only from how many transactions there are.

Built to investigate, not to reconcile

Green screens are designed to look up a known exception, not to reconcile a full population of transactions. To query anything, you already need the right identifier: the STAN (system trace audit number), the merchant or the terminal.

When the day’s balance doesn’t match the bank statement, the screens offer no drill-down. The analyst has to work backward through several screens and into a spreadsheet to find the difference.

There’s also a recurring date mismatch. The processing date used for daily verification doesn’t always line up with the effective date the bank uses. That breaks the balance on a regular basis, even when nothing is actually wrong.

Face value numbers without the detail behind them

Much of what teams see in these views are bulked amounts. For example, a single $1,000,000 settlement figure is a face value number. It says how much moved, but not which transactions, fees and adjustments make up that total. Reconciling at this aggregate level (high-level totals with no transactional detail) leaves variances unexplained until someone investigates them manually.

Raw TSYS files are hard to read

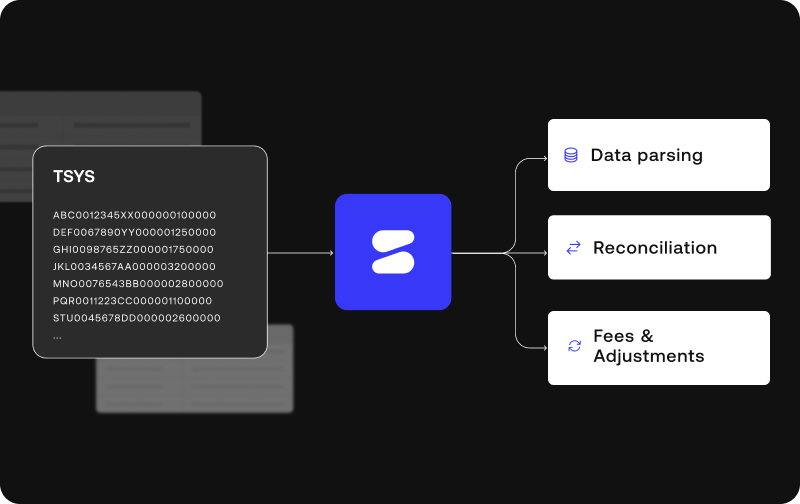
The underlying data exists, but not in a usable form. TSYS delivers financial movement data as large, unstructured files made of dense character strings and code lines, without the readable columns a finance team would expect. Before anyone can calculate or match against this data, it has to be parsed and converted into structured tables.

What this costs finance teams

Every figure copied from a terminal screen adds validation work to each downstream journal entry. The process depends on the few people who know how to navigate the screens. And each manual step is another chance for an entry error that ends up in the books. Transaction-level matching becomes too labor-intensive to run every day, so most teams settle for reconciling totals and investigating differences after the close.

How Simetrik transforms TSYS data into verified, transaction-level detail

Simetrik is an AI-native financial control platform. Its core is transaction-level reconciliation. For TSYS clients, Simetrik works from the raw data files TSYS delivers rather than from green screens. It turns those files into a structured, rule-based reconciliation workflow.

Data parsing: turning raw TSYS output into readable tables

Simetrik ingests TSYS files through compatible methods. It parses the unstructured strings into clean, tabular data with defined columns, dates and amounts. AI can suggest how to interpret non-standard file layouts, and the team reviews a preview before the configuration is applied.

The value is that the team no longer has to rebuild the day’s numbers by hand from screen after screen.

Financial reconciliation: unpacking bulked amounts

With the data in structured form, Simetrik can compare three things: the transaction-level detail behind each settlement, the net deposit in the bank statement, and the entries in the ledger. Matching rules can relate one deposit to the many transactions it contains. Tolerances and timing rules can account for the gap between processing date and effective date.

A face value number stops being a black box. Records that match are separated from the ones that don’t, and each exception is traced to the rule that flagged it.

Automated enrichments: fees, adjustments and deductions

Simetrik applies configured calculations, transformations and enrichments to the parsed data. These cover interchange, processing fees, authorization fees, adjustments and deductions. This makes it possible to rebuild the path from gross transaction volume to the net amount deposited, and to see where the two diverge.

Chargebacks, reversals and adjustments can be brought in as their own data sources. They’re then matched back to the original transaction and settlement. A late change shows up as a specific exception to investigate instead of an unexplained variance in a period the team thought was closed.

Auditable by design

AI helps teams configure and adapt matching logic when file layouts, merchant portfolios or volumes change, including through natural-language setup. The matching itself runs on a deterministic core. With the same data and the same rules, Simetrik produces the same result. Every match, exception and manual action can be traced back to a visible rule and a named reviewer.

Business impact: automated tracking of financial movements

For TSYS clients, the shift is from checking totals to verifying transactions:

  • Less manual effort. Analysts spend less time copying numbers across green screens and rebuilding daily balancing templates, and more time investigating the exceptions that matter.
  • Lower operational risk. Fewer hand-keyed figures mean fewer entry errors reaching the books and less dependence on the few people who know the screens.
  • Clarity on money movements. Bulked amounts are unpacked into the transactions, fees and adjustments behind them, so the team can explain the gap between processed volume and net deposits.
  • Cleaner inputs for accounting. Verified, transaction-level data gives downstream journal entries a traceable source, which reduces the extra validation each entry needs today.
  • Better control of financial discrepancies. Teams can identify incorrectly charged fees, unexpected charges, and chargebacks that are missing, mismanaged, or incorrectly accounted for, making it easier to investigate and recover discrepancies.

See how Simetrik reconciles your TSYS acquiring data, from raw file to ledger. Book a demo.

Frequently asked questions

Is TSYS a reconciliation platform?

No. TSYS is a payment processing platform. On the acquiring side, it authorizes, clears and settles card transactions for merchants and reports on that activity. It doesn’t reconcile that activity against a client’s bank accounts or internal ledger. That verification is the job Simetrik is built for.

Why is reconciling TSYS acquiring activity harder than it sounds?

A single merchant portfolio on TSYS generates several parallel data streams, and they rarely arrive at the same time or in the same file. These include authorizations, cleared transactions, settlement batches, netted fees, chargebacks and adjustments. As the number of merchants, entities or currencies grows, so does the number of streams to align. That makes manual tracking harder to sustain.

What is the typical process for checking financial movements in TSYS?

Many finance teams check financial movements by logging into legacy green screens and reviewing bulk totals. They then copy those face value numbers into daily balancing spreadsheets and compare them against bank statements and ledger entries. Because this depends on manual copy-paste, matching usually happens at the aggregate level rather than per transaction. With automated ingestion, the raw TSYS data is parsed and matched at the transaction level instead.

Why are TSYS data files so difficult to parse for financial reconciliation?

TSYS delivers financial movement data as unstructured files made of dense character strings and code lines, with no readable column structure. Before any calculation or matching can happen, those strings have to be parsed into tabular data with defined fields such as dates, amounts, merchant identifiers and fee types. Simetrik handles that parsing as the first step of the reconciliation workflow.

How does Simetrik handle fee calculations, adjustments and bulked amounts from TSYS?

Simetrik ingests the bulked amounts (face value numbers) along with the underlying TSYS data and parses the line-item detail. It then applies configured fee calculations, adjustments and deductions. This lets teams rebuild how gross volume becomes the net deposit, and match each component against the bank and the ledger. Differences are flagged as exceptions for review.

Why do many organizations use processor portals?

Processor portals and reporting interfaces give teams operational views of processing activity. They’re used to monitor authorizations, pull daily settlement reports and handle administrative tasks such as chargeback responses. They’re built to report on processor output, not to run transaction-level financial controls. Finance teams still have to extract that data and reconcile it against their bank deposits and accounting records.

Which legacy tools, such as green screens, create bottlenecks in TSYS reconciliation?

Many acquiring banks and ISOs still rely on 3270 terminal green screens to verify daily balancing totals. These screens have no export function, so analysts copy and paste figures across multiple screens by hand. This creates dependence on a few key people and increases the risk of data entry errors. It also adds audit risk to every downstream accounting entry built from those numbers.

How does Simetrik work with TSYS data?

Simetrik works with the files and reports TSYS delivers to its clients, not with the green screens. It ingests settlement, clearing, fee and adjustment data alongside bank statements and ledger data, parses it into structured tables and applies configured matching rules. Matched records are separated from exceptions that need investigation.

Do TSYS clients still need a separate reconciliation platform?

Usually, yes. TSYS processes the transactions, but it doesn’t check that what it processed matches what settled into the bank and what’s recorded in the ledger. For clients with growing merchant volume, multiple data streams or manual green-screen processes, that independent check is where a reconciliation platform like Simetrik fits.

Managing liquidity in an age where money moves faster than ever

Payments increasingly move in near real time across banks, payment service providers, card networks, platforms, and internal systems. Each participant can record a different amount, timestamp, fee, or settlement status, making liquidity visibility harder to maintain.

This complexity greatly complicates the role of treasury and finance teams. Variance among currencies, settlement times, and data management protocols makes it hard to track liquidity and accurately apply cash at scale, often leading to millions of unaccounted-for dollars a year. 

How can the office of the CFO tackle liquidity and forecasting challenges when money moves faster than it ever has? Keep reading for the answer – and a look into the emerging world of AI reconciliation.

The short answer: reconcile transaction, settlement, bank, and internal records frequently enough to identify what has cleared, what is pending, and where exceptions remain. Reconciliation improves the data used for liquidity decisions, but it complements rather than replaces a treasury management system, cash forecasting, or funding execution.

What’s so hard about liquidity management?

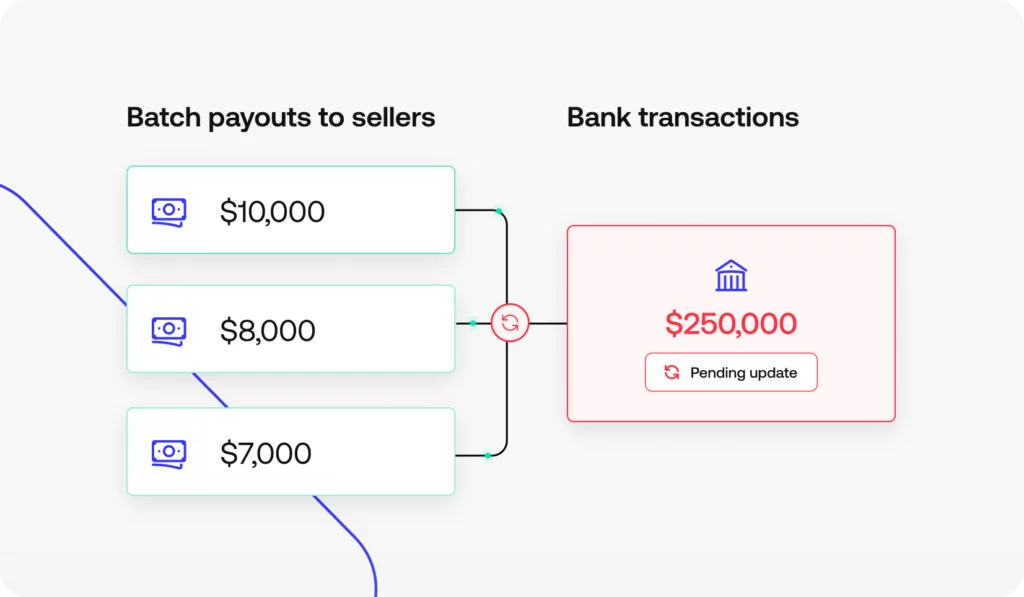
Batch seller payouts compared with a pending bank balance update

Treasury and finance teams used to be able to rely on batch settlement data to understand their cash positions. With the proliferation of flexible payment methods and new payment services, complexity grew. 

The addition of real-time payment (RTP) networks brings even more nuance and risk to the market. These new payment rails give businesses faster ways to handle payroll, pay out merchants, and manage AR/AP – they also tend to push internal reconciliation and finance teams to the limit.

The challenges to managing liquidity effectively today include:

  • Funds come and go many times throughout the day. Without a continuous tracking system, finance teams can’t be sure enough cash is available at any given point.
  • Settlement times vary and don’t always coincide with transaction time stamps. Bank balances may be off by thousands of dollars, leading to poor funding decisions, unplanned fees, and unnecessary panic. 
  • Batch payments don’t map back to individual transactions. This adds hours of manual reconciliation to ensure cash and fees are applied correctly.
  • Discrepancies and errors slow reconciliation and make it hard to calculate cash on hand. 

Move too cautiously, and the opportunity cost is steep. Cash sits idle in accounts instead of being deployed to fund growth or reduce short-term borrowing. Move too aggressively, and you risk the opposite problem.

Underfunded RTP accounts, for example, can break funding agreements with sponsor banks – the very relationships that make instant payments possible. Without timely reconciliation, teams may not realize how quickly real-time payouts are draining balances until transactions start failing.

Cross-border settlements introduce another layer of complexity. Funds often pass through multiple correspondent banks and FX providers before reaching their destination. When timing or conversion delays aren’t captured immediately, treasury teams can mistake in-transit balances for available cash, exposing the business to liquidity gaps and currency risk.

Merchant payouts add risk, too, as marketplaces and retailers often pay merchants ahead of card network settlement. Without clear visibility into pending inflows, finance teams may overextend working capital, effectively funding payouts with money that hasn’t yet arrived.

To accurately monitor liquidity and maintain a clear line of sight into balances, AR, and AP across  your entire payments ecosystem, look no further than reconciliation. 

The role of reconciliation in understanding liquidity 

Reconciliation helps finance teams manage liquidity and cash flows by maintaining accuracy and financial integrity at every step of every transaction.

At the most granular level, the reconciliation process validates and matches transaction records across all parties. At a higher level, it ensures operational balances accurately reflect the reality of the company’s cash position.

Once reconciled, the data can be used to make all kinds of decisions about liquidity: whether to acquire more funding, what payment terms to offer or accept, how to allocate working capital, and many more. 

But while AI and automation have transformed other key enterprise workflows, too many companies have yet to invest in modern reconciliation solutions that can handle the volume and complexity associated with real-time, global payments today.

The problem with legacy financial platforms

Many finance teams still rely on manual entries, spreadsheets, and brittle systems that can’t paint a real-time picture of cash flows and liquidity. Even with a strong treasury management system (TMS), the gap between balances shown in banking systems or financial analytics tools vs the reality of minute-by-minute transactional data leads to substantial discrepancies and excess costs.

Legacy, manual solutions aren’t just slower, they suffer from poor interoperability – too many disparate data formats, currencies, and protocols muddy visibility and hinder finance teams’ ability to use reconciled data for critical decision-making around liquidity. 

Fragmented tech stacks also force engineering to spend time on costly integrations and workarounds, rather than working on initiatives that will eventually drive revenue. The bottom line? It’s expensive to stick to the status quo.

How transaction reconciliation improves liquidity visibility

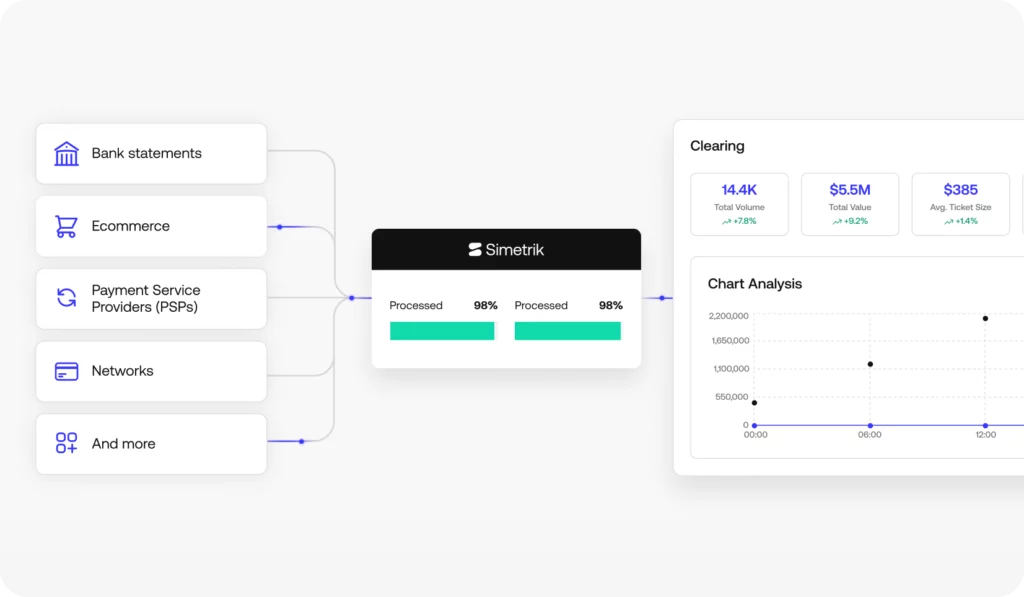
Bank, ecommerce, PSP, and network data feeding a reconciliation dashboard

AI-assisted reconciliation helps finance teams improve the accuracy and timeliness of data used for working-capital and funding decisions. Modern platforms apply deterministic matching rules at scale, surface exceptions, and produce traceable dashboards and reports for treasury and finance teams. 

These newer, AI-enhanced systems are designed to handle exactly the kind of high-volume, complicated transaction data that enterprise finance teams struggle with. Incoming and outgoing payment records can be validated and matched across PSPs, real-time payment rails, card networks, banks, and internal systems, with exceptions routed for review. 

Unlike legacy and manual solutions, AI reconciliation centralizes all of your transaction and finance operations data into a single source of truth, standardizing records and identifying gaps so operational balance views can be refreshed as new data arrives. This gives teams a more reliable view of cleared, pending, and unmatched activity that can inform prefunding decisions on real-time payment rails. 

Treasury and finance decision-makers can log into their TMS, business intelligence tools, ERP, or any other connected system and work from the same reconciled dataset, reducing uncertainty in liquidity analysis.

Strengthen liquidity with complete visibility and control on Simetrik

Simetrik is an AI-assisted reconciliation platform for complex finance operations where liquidity decisions depend on timely, traceable transaction data. 

The platform ingests transaction data from any source and system, standardizing it and applying configurable, deterministic matching logic. Reconciled outputs and exception data can then feed connected ERPs, treasury systems, and business intelligence tools.

This level of automation and efficiency lets your finance team spend less time on repetitive matching and more time reviewing exceptions and supporting forecasting. Depending on the workflows and data sources configured, teams can use Simetrik to:

  • Compare operational balances with transaction and settlement data
  • Include prepayments and credits in reconciled balance views
  • Batch payouts and bulk payments from PSPs are automatically disambiguated
  • Surface aging receivables for follow-up in connected workflows
  • Fraud and risk models are improved with trusted, reconciled data
  • Detect errors and route discrepancies for governed resolution
  • Feed reconciled data into the TMS and ERP for liquidity analysis

Simetrik helps finance and treasury teams transform their operations while maintaining global governance and control. To learn more about how our AI reconciliation platform improves liquidity and drives profitable decision-making, explore our solutions or get in touch with us to schedule a demo.

Payments reconciliation automation: a practical guide

If you work in card payments, you know the feeling. A network file lands at 3:07 a.m., a processor export arrives at 3:12 a.m., and by 9:00 a.m. the operations team is trying to explain why a handful of transactions do not line up. Meanwhile, compliance wants sub-merchant chargeback trends and engineering is preparing another rule change and redeploy.

Payments reconciliation is the process of comparing transaction records across processors, card networks, banks, and internal systems to confirm that amounts, references, fees, refunds, and settlements agree. Automation brings those records into one controlled workflow, applies matching rules, and routes exceptions for review.

This matters most in high-volume payment operations, where the same transaction can arrive with different identifiers, dates, formats, or statuses. A processor file may land overnight, but operations still needs to explain why a subset of records does not line up the next morning.

This guide explains how to automate payments reconciliation from data ingestion and normalization through matching, exception analysis, alerts, and traceable reporting. The working example compares processor records with network settlement data, but the same pattern applies when several processors need to be reconciled against one ledger or settlement view.

Why payments reconciliation breaks at scale

  • Fragmented data: Networks, processors, gateways, banks, internal ledgers, ERPs, settlement files, and dispute feeds each have their own identifiers, formats, timing, and lifecycle.
  • Frequent change: Networks revise specifications, partners add columns, merchants expand cross-border, and teams launch new payment products. A code-only workflow can struggle to keep pace.
  • Engineering bottlenecks: When matching logic lives entirely in code, a small adjustment can require a ticket, a pull request, testing, a redeploy, and cross-team coordination.
  • Limited visibility: Finance and operations may know the totals but still need to trace root causes, fee variances, or sub-merchant chargeback trends through SQL, email threads, and several systems.

Five building blocks of automated payments reconciliation

1. Ingest source data

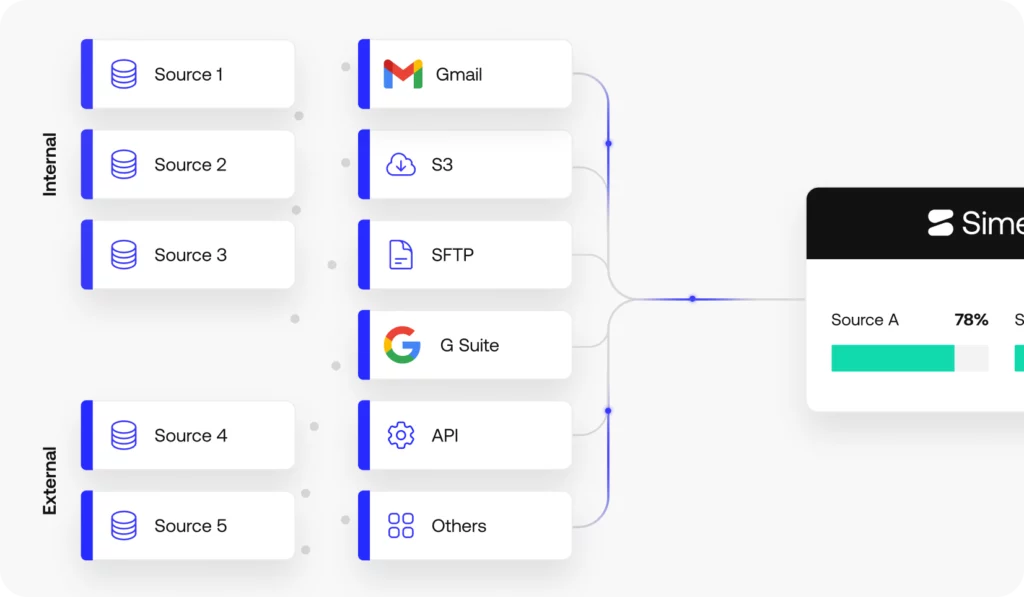
Internal and external data sources flowing into Simetrik through email, S3, SFTP, Google Workspace, and APIs

Start with the records that describe each stage of the payment lifecycle: processor exports, network settlement packages, bank statements, dispute feeds, and internal ledger data. Preserve the source context and original structure so every output can be traced back to the record that produced it.

Simetrik can ingest financial and operational data through compatible methods such as SFTP, email, APIs, or secure access workflows.

When a PDF or flat file contains 30 tables, the tabular sections can remain distinct Sources while retaining the original structure for audit. The objective is a governed input layer without brittle preprocessing scripts or staging jobs.

2. Normalize records across sources

Different systems use different column names, date formats, signs, currencies, and reference fields. A processor may add Ref2 beside Ref1 or insert a new field without changing the underlying transaction. Normalization makes those records comparable before matching begins.

Source Unions map compatible partner files into a consolidated schema. If Visa changes a column name or a processor inserts a field, the team can update the mapping while preserving historical context.

Dozens or hundreds of compatible partner sources can feed a canonical view for comparison with an internal ledger or network settlement data. AI-assisted mapping can suggest relationships between columns, while the team reviews the configuration and its downstream dependencies.

Reconciliation should not break because someone added Ref2 next to Ref1. Normalization is an operational capability, not a one-off cleanup project.

3. Apply configurable matching rules

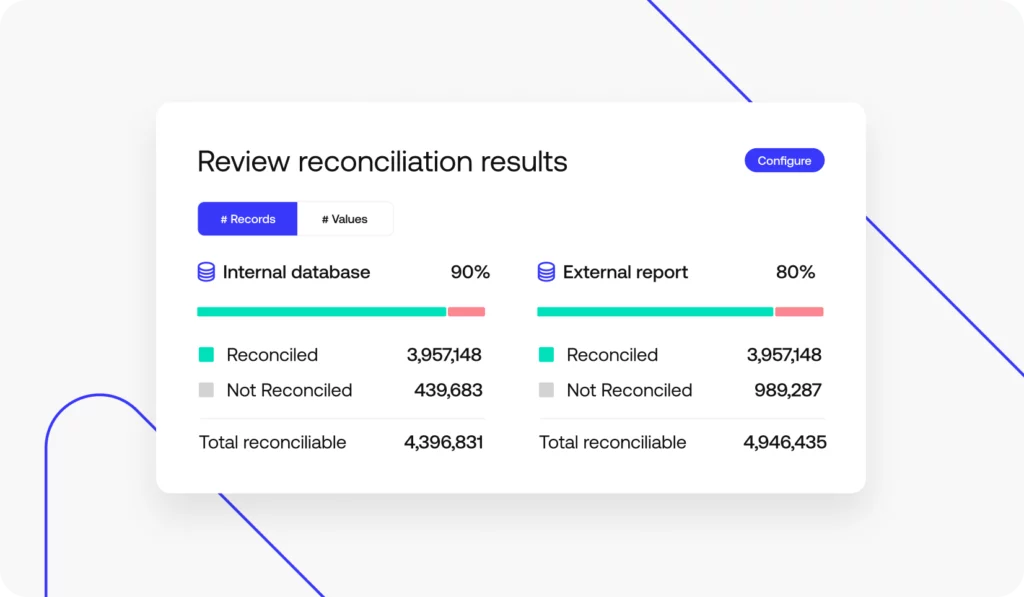
Simetrik reconciliation results comparing matched and unmatched records from internal and external data sources

Start strict with amount, currency, multiple references, payment method, and an approved settlement-date tolerance such as T+1. Then add priority-based fallback logic for a secondary reference parsed from a longer string, known timing differences, minor rounding, or processor-specific behavior.

Some customer configurations use Rule Sets in the triple digits to cover the long tail. Each match remains tied to the Rule Set that produced it.

Simetrik applies configured rules deterministically: the same data and configuration produce the same control result. AI can assist with suggestions, but the team remains responsible for validating the logic.

Operations should not need an engineering ticket for every documented rule change. Moving that configuration out of a code-only workflow avoids a pull request and redeploy while preserving ownership, history, and review.

4. Analyze matches and exceptions

Each run should separate matched records from exceptions and make the remaining work easy to investigate. Useful views include:

  • Match rate and unmatched value for the current run.
  • Exceptions by processor, payment method, merchant, or geography.
  • The rule set that matched each record.
  • Fee, foreign exchange, and settlement variances.
  • Chargeback activity linked to the underlying transaction.

Simetrik’s Operations Center can bring reconciliation results, anomalies, and pending items into one environment so teams can investigate and document exceptions with their supporting context.

Reconciliation is not only about making two files equal. Teams need to move from transaction-level evidence to executive summaries, then back to the exact row and Rule Set that explains a result.

5. Monitor controls and completeness

Configured alarms can flag an expected file that did not arrive, a row-volume change, a falling match rate, a chargeback spike, a fee variance, or a growing exception backlog. Thresholds should reflect materiality: three unreconciled transactions totaling $250,000 may deserve attention before 300 records totaling $12.60. Track amounts, not only counts.

Simetrik can monitor configured conditions, alert teams to signals that need attention, and bring related work into its unified oversight and alerts layer.

How to automate a processor-to-network reconciliation

A processor-to-network reconciliation usually follows six controlled steps.

Step 1: Collect the records

  • Acquirer or processor transaction exports, delivered through the agreed workflow.
  • Visa or Mastercard network settlement packages, kept distinct when their lifecycle requires it.
  • Optional bank statement, refund, dispute, or chargeback data.

Set a clear owner and expected delivery cadence for each source. A reconciliation cannot be complete if one of its required inputs is missing.

Step 2: Normalize the source data

  • Map processor fields into a common structure for dates, amounts, currencies, statuses, and multiple references such as Ref1, Ref2, and Ref3.
  • Keep network records separate when their structure or lifecycle requires a different preparation path.

Step 3: Enrich the fields needed for matching

Add calculated or standardized fields only when they help compare the records. Examples include normalized timestamps, fee-per-transaction calculations, foreign exchange conversions, or a fallback reference extracted from a longer entry string. Document every transformation so it can be reviewed later.

Step 4: Define matching logic

  • Strict rule: Match amount, currency, primary reference, payment method, and an approved settlement-date tolerance.
  • Fallback rule: Use a secondary reference or a wider timing tolerance for known operational differences.
  • Edge-case rule: Apply specific logic for gateway quirks, cross-border FX rounding, partial captures, refunds, or other understood lifecycle differences.

Run rule sets in priority order and retain the rule that matched each pair. That record makes later review much easier.

Step 5: Review exceptions

  • Group unmatched records by cause, source, value, and age, then expose the exact failure reason, such as a missing reference, amount variance, or settlement drift beyond tolerance.
  • Assign an owner, evidence, and next action to material exceptions.

Step 6: Act and distribute results

  • Trigger configured alerts when a control crosses its threshold.
  • Export or distribute daily summaries, settlement confirmations, fee breakdowns, and other reconciled data through compatible reporting workflows.
  • Retain the original sources, transformations, rules, user actions, and timestamps needed to reconstruct the result.

How chargebacks fit into payments reconciliation

A chargeback should connect back to the original payment, the processor or network notification, any financial debit or fee, the settlement result, and the internal ledger.

When those records live in separate systems, teams can miss duplicate debits, unmatched fees, a recovery that never appears in settlement, or a chargeback deduction with no underlying transaction match.

  • Validate that each dispute is linked to a valid transaction and the expected financial movement.
  • Track both counts and amounts by sub-merchant, brand, country, BIN, processor, and the other operational dimensions that matter to the team. A small count can still represent a material financial exposure.

Simetrik can compare compatible sources, follow exceptions, and verify the financial impact of a result. Its claims and chargebacks workflow focuses on transaction-level control across that lifecycle.

Performance and scale: what enterprise buyers should test

A natural evaluation question is: what happens when a million transactions run through dozens of Rule Sets? The answer has to cover more than raw throughput. Buyers should test whether runtime stays predictable as volumes grow, sources change, and new edge cases are added.

Simetrik customer environments can reach hundreds of millions of records per day across multiple reconciliations, with execution measured in minutes. Matching is parallelized, transformations compile efficiently, and Source Unions reduce the rework created by one-off pipelines.

The practical test is whether teams can add Rule Sets for gateway quirks, settlement drift, FX rounding, partial captures, and refunds without pushing a nightly run into the next business day. Track daily volume, Rule Set count, end-to-end runtime, peak-load behavior, and the cost of adding each new exception pattern.

Metrics for automated payments reconciliation

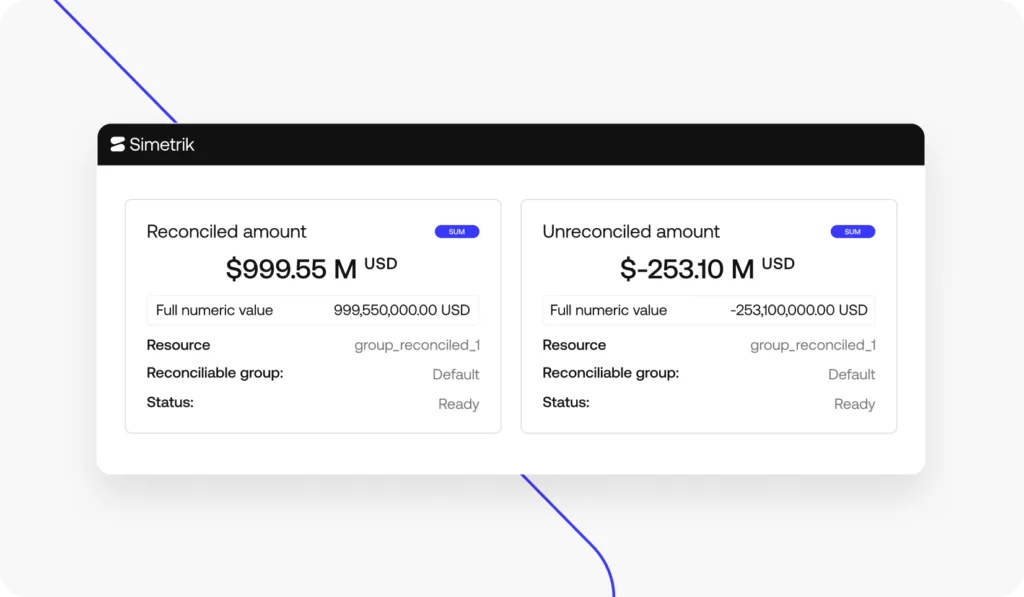
Simetrik dashboard showing reconciled and unreconciled amounts for a reconciliation workflow

A useful dashboard should show whether the process is complete, accurate, timely, and explainable. Track:

  • Match rate and value coverage: The share and value of records matched by the configured rules.
  • Unmatched count and value: The volume and financial materiality of the remaining exceptions.
  • Exception aging: How long unmatched items remain unresolved.
  • Time to resolution: The elapsed time from detection to a documented outcome.
  • Fee and FX variance: Differences between expected and recorded deductions or conversions.
  • Source completeness: Whether every required file or dataset arrived for the run.
  • Manual intervention rate: The share of records that required judgment or adjustment.

Targets should reflect materiality, source quality, and the risks of the workflow. In mature implementations, teams using this approach have reported daily match rates above 99.95%, with the remaining exceptions explainable and trending down. Treat that as a benchmark to validate against your own data, not as a universal guarantee.

Build vs. buy: what to evaluate

An internal solution can fit a narrow, stable workflow with a strong technical owner. The honest comparison begins when sources, entities, rules, and exceptions keep changing. Evaluate time to adapt, engineering dependency, long-tail coverage, auditability, and opportunity cost, not only the first version of the matcher.

CriterionBuild in-houseUse a platform
Change frequencyYou own development, testing, releases, and maintenance.Evaluate configurable rules, approvals, and versioning.
Source growthYou build and maintain ingestion and transformations for each source.Verify compatible ingestion and normalization methods.
Exception ownershipYou design queues, service levels, and escalation paths.Evaluate assignment, evidence, and traceability in one workflow.
AuditabilityYou implement history, permissions, and row-level evidence.Verify lineage, action logs, and reproducible results.
EconomicsCount infrastructure, support, and key-person risk.Count implementation, subscription, and vendor dependency.

Long-tail coverage is where the economics often change. In the in-house programs observed by Simetrik, initial automation has reached roughly 60% coverage before edge cases began consuming disproportionate engineering time.

The relevant comparison is not only license cost versus infrastructure. It also includes sprint time, support, key-person risk, audit controls, and the opportunity cost of taking engineers away from customer-facing or risk work.

Neither option is automatically better. A platform becomes more compelling when change is frequent, exception logic expands, and operations needs direct control without giving up auditability. That is the point at which Simetrik’s configurable rules, Source Unions, controls, and transaction-level traceability address more than the matching step.

A practical pilot plan

A six-week pilot can provide a useful evaluation window when the sources, owners, and scope are ready. This is an outline for testing coverage, control, and runtime against a known baseline, not a universal implementation promise.

  1. Week 0–1, connections: Set up compatible delivery for processor, network, and optional bank or chargeback data. Confirm owners and expected arrival times.
  2. Week 1–2, normalization: Build the Source Union or equivalent canonical views. Add the three to five enrichment fields needed for fees, FX, timestamps, or parsed references.
  3. Week 2–3, first reconciliation: Configure three to five prioritized Rule Sets and test them against historical data, including known exceptions.
  4. Week 3–4, exceptions and dashboards: Create root-cause views, define owners and evidence, add chargeback or sub-merchant views where relevant, and configure alerts.
  5. Week 4–5, iteration: Add long-tail Rule Sets for documented edge cases and validate the reports or exports the receiving teams require.
  6. Week 6, review: Compare runtime, match rate, unmatched value, exception aging, and manual effort with the baseline before expanding to more processors, networks, or bank settlement workflows.

Make reconciliation predictable

Reconciliation will never be glamorous, but it should be predictable, explainable, and fast. A partner changing a column on Thursday should be a controlled mapping update, not a post-mortem.

Automated payments reconciliation works when complete source data, documented transformations, deterministic rules, visible exceptions, and an audit trail make every result reconstructable while human review remains where judgment is required.

Simetrik brings data preparation, deterministic matching, exception management, and traceability into one transaction-level reconciliation workflow. To test it with your own processor, network, bank, or chargeback data, request a demo.

Scaling real-time payments: key challenges for PSPs

By 2029, global payment revenues are expected to reach $2.4 trillion. That’s an increase of over 25% from today’s figures, spread across a fragmented landscape of banks, card schemes, clearinghouses, payment processors, and other payments stakeholders.

Real-time payment rails have added a new level of complexity and opportunity to the landscape. These networks make it possible to move money between participating institutions in seconds, often with 24/7 availability. Payments service providers (PSPs) are embracing instant payments to stay competitive, but the move doesn’t come without risk.

As instant payments scale, banks and PSPs face five connected challenges: sponsor bank and third-party dependencies, 24/7 liquidity, fragmented data and reconciliation, fraud exposure, and evolving compliance requirements. For PSPs scaling real-time payments for lending platforms, fintech startups, merchants, payroll providers, and digital wealth products, these challenges align with Federal Reserve guidance on fraud, liquidity, compliance, and third-party risk.

As customers demand more immediacy and convenience, PSPs must closely examine their technology investments and financial partners to optimize the benefits of real-time payments. As you plan for scale at your own organization, make reducing complexity a top priority for your finance team.  

The challenges of scaling instant payments

Real-time payments haven’t been around for long, but they’ve transformed the industry. The Unified Payments Interface (UPI) in India launched in 2016, the US-based Clearing House’s RTP Network launched in 2017, and Brazil’s Pix went live in 2020. Alongside counterparts in more than 70 countries, these networks now process trillions of dollars in real-time payment volume each year.

These rapidly adopted payment rails enable PSPs to offer faster, more convenient ways for merchants to accept customer payments. From a user perspective it’s easy to make instant payments on these platforms, but behind the scenes there are many moving parts that often eat into margins and cause regulatory confusion.

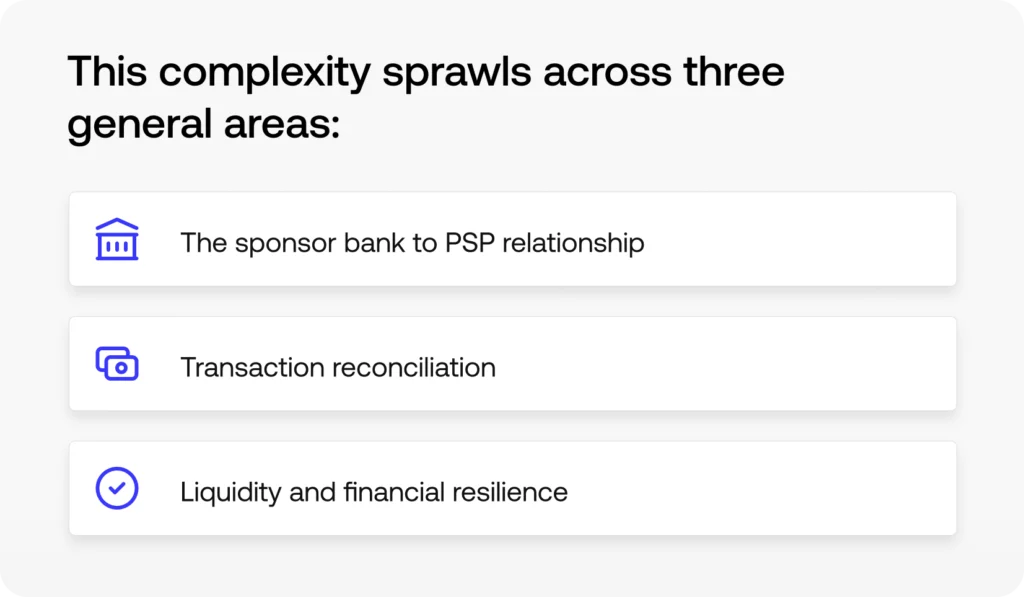
Three instant payment scaling challenges: sponsor bank relationships, transaction reconciliation, and liquidity

Let’s dive into each of them.

The sponsor bank relationship: a delicate balancing act 

Finding the right sponsor bank is key to your long-term success as a US PSP. To select the best partner, ensure agreements are structured to optimize outcomes on both sides. 

First, consider which regions you operate in now or plan to in the future. For PSPs scaling cross-border payments, partnering with banks that already connect to multiple RTP networks can reduce integration complexity and make expansion easier. Talk through how quickly you can enable payments via networks like the EU’s SEPA Instant Credit Transfer (SCT Inst), India’s UPI, and Singapore’s FAST, even if you’re not currently in those regions. 

Next, examine the bank’s technology. Make sure they have robust infrastructure and integrations in place to support a large volume of real-time transactions on your platform without disruption. Ask about their adoption of shared standards like Swift GPI and ISO 20022 XML V9 to understand the reconciliation roadblocks you may encounter. Check for strong risk management and liquidity guardrails that keep money moving even if volumes spike unexpectedly.

Then discuss the bank’s available funding models, including the pros and cons of each and how much flexibility you’ll have to move among them. Banks and credit unions typically offer one or more of the following modes:

  • Pre-funding agreements – PSPs deposit a certain amount at the sponsor bank to cover transactions up to that balance. This is a simple, low-risk option for the bank but requires you to tie up a significant amount of working capital and may pause transactions if the account falls below its threshold. However, variations on these models offer more flexibility, like just-in-time top-ups or hybrid pre-funding/credit models that keep transactions moving if volumes surpass the agreed threshold.
  • Intraday sweeps – The sponsor bank monitors RTP volume and sweeps funds from PSP accounts throughout the day. This option reduces the need for large prefunding deposits but requires constant reconciliation and clear visibility into liquidity to be effective. If you’re still using legacy finance systems or struggling to reconcile payments at the transaction level, this model might not be feasible.
  • Credit lines – The sponsor bank extends credit to PSPs, funding RTP activity to a certain limit and interest rate. Batch settlements occur via ACH daily, weekly, or monthly, complicating the reconciliation process but freeing up significant capital for the PSP. 

Selecting the right sponsor banks and funding models is important, but in reality even the best partnerships can’t solve all of the big-picture challenges around reconciliation, liquidity management, and revenue leakage in today’s instant payment ecosystem.

The reconciliation challenge

Reconciliation, or the process of validating and matching transactions to ensure financial integrity, becomes nearly impossible at the volume and complexity described above. The sheer number of partnerships, regulatory bodies, consortiums, and technologies needed to support instant payments across traditional and emerging systems calls for an entirely new approach to reconciling and managing transaction data.   

Even at the enterprise level, many finance teams are still using spreadsheets and semi-manual processes to check each transaction against bulk settlements, fee deductions, and other activity along the payment journey. This gap between sending and receiving real-time payments and clearly tracking their business impact leads to major issues: revenue leakage, excess spending, and painfully drawn-out audits and close cycles. 

To reconcile instant payments accurately and cost-effectively, PSPs must have a clear view of the entire RTP value chain in one place. But because these networks are fairly new and run by disparate government and hybrid public/private entities, there is still limited interoperability between them. 

The effect of real-time payments on liquidity

PSPs that don’t address these challenges will find that instant payments hinder their liquidity and financial health. Lack of visibility at the transaction level leads to poor working capital management and blind decisions around financing, while losses due to reconciliation errors, fraud, and missed collections directly eat into available cash. 

Paired with the right partners and technology, however, real-time payments boost your financial resilience and help you retain customers in a crowded market. Modern reconciliation platforms automate your finance team’s most error-prone, inefficient workflows, making it possible to process and reconcile millions of real-time transactions each day.  

Reconciliation also makes it easier to optimize your agreements with sponsor banks. Keeping a healthy balance in the accounts connected to RTP rails is key for any pre-funding, sweeps, or hybrid model, and having full visibility into the details of past transactions helps predict future demand so you always have appropriate funding in place.

Once reconciliation isn’t a blocker, instant payments become a strength. Instead of worrying about a sudden lack of working capital, you can focus on providing cutting-edge services to your customers. 

Simetrik: AI reconciliation for the instant payment era

Simetrik is a comprehensive transaction reconciliation platform that unifies data across every system involved in real-time payments, automates multi-way matching, and exposes exceptions before they become a problem.

PSPs rely on Simetrik to achieve new levels of scale and auditability across four distinct areas:

  • Cost control and fee management – Expose, validate, and optimize all of the fees associated with RTP rails.
  • Cash position and liquidity – Accelerate settlement, reduce working capital drag, and improve forecasting and visibility.
  • Regulatory reporting – Reduce risk and automate reporting across SOX, PCI, GLBA, and other obligations.
  • Cross-border and crypto transactions – Tame FX, network variance, and on/off-ramp complexity with reliable, scalable reconciliation.

By 2028, real-time payments will account for over a quarter of global electronic payments. To learn how Simetrik streamlines RTP complexity and turns this fast-evolving market into a strategic profit lever, request a demo of our platform.

Streamline reconciliation with preconfigured solutions for acquirers

Acquirers play a pivotal role in the modern financial ecosystem, facilitating card payments and disbursing the right amount to merchants with every purchase. But each transaction is a potential point of failure that’s subject to risk from errors, disputes, and revenue leakage.

How can acquirers reduce manual reconciliation? By standardizing scheme files, settlement records, bank statements, and internal transaction data, then applying reusable matching and fee-validation rules. Preconfigured workflows shorten setup time while keeping exceptions and rule changes visible to finance teams.

To handle high transaction volumes and maintain your reputation in a fragmented payments market, you must reliably automate reconciliation and reporting—starting with activity related to the card networks that make up a major portion of your transactions.

Simetrik’s preconfigured Visa and Mastercard solutions make this possible without exorbitant costs or a heavy engineering lift. It’s designed to help you set up best-practice reconciliation workflows with no code, guided by an intelligent setup assistant and a dedicated onboarding team, and maintain full visibility into the inner workings of your rulesets and logic as they evolve.

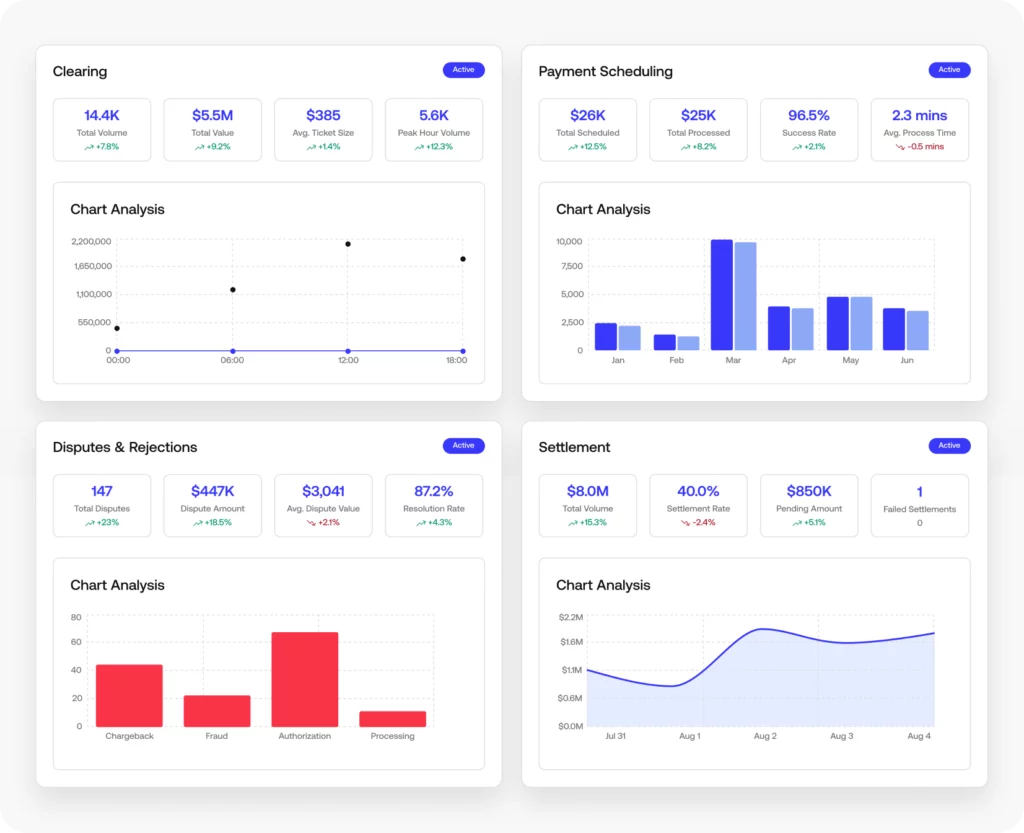
Acquirer dashboards for clearing, payment scheduling, disputes, and settlement

We’ve connected nuanced capabilities and financial controls to enable six key use cases, from authorization to dispute management, in a way that’s easy to deploy and adopt.

Why should acquirers automate reconciliation?

Monitoring and reconciling card network transactions is critical to your success as an acquirer. Visa and Mastercard not only make up a large portion of total transactions, they also each have their own set of requirements for acquirers, including specific audit frameworks and scheme fees that must be tracked meticulously.

Simetrik automates reconciliation down to the transaction level, matching records across internal and external systems and generating traceable outputs for merchants, auditors, and other stakeholders. Reporting workflows can be configured to support relevant Visa and Mastercard data requirements. Instead of managing spreadsheets and scrambling to organize data for network reports like the QMR (Mastercard Quarterly Member Report) and GOC (Visa Global Operating Certificate), you can focus on quickly remediating errors and disputes.

Once data is reconciled and verified, it can be used by your team and your merchants to make better operational decisions, from forecasting to fee strategies.

5 reasons to automate Visa and Mastercard reconciliation:

  • Improved cash-flow visibility
  • Better forecasting inputs
  • Efficient fee management
  • Faster dispute resolution
  • Stronger risk management

6 key functionalities you can enable on Simetrik

Simetrik connects acquirer-supplied scheme files, bank statements, and records from internal systems like your ERP, automating six key reconciliation use cases for Visa and Mastercard transactions:

  • Funding – Validate programmed versus received bank receipts, investigating partials or delays to ensure compliance and timely execution.
  • Authorization – Ensure control and reduce fraud by reconciling authorized requests and responses with network data and matching clearing files to issuer records.
  • Clearing – Validate scheme fees, interchange fees, and network adjustments against acquirer records to prevent overbilling and missed charges.
  • Disputes – Confirm funds debited from issuers, reconcile pre-arbitration and arbitration cases, and help merchants manage evidence.
  • Settlement – Calculate daily net settlement and validate receipts against bank statements to improve settlement and funding visibility.
  • Agenda – Split domestic and international agendas, with or without deferment, validating expected financial movements to prevent loss from delayed or missing settlements.

Minimize risk with fast, guided deployment

Simetrik leverages a dedicated onboarding team alongside AI-enhanced setup flows to help you quickly improve reconciliation and reporting. The platform reduces repetitive manual handling while keeping users in control of final outputs through governed workflows and visible reconciliation logic.

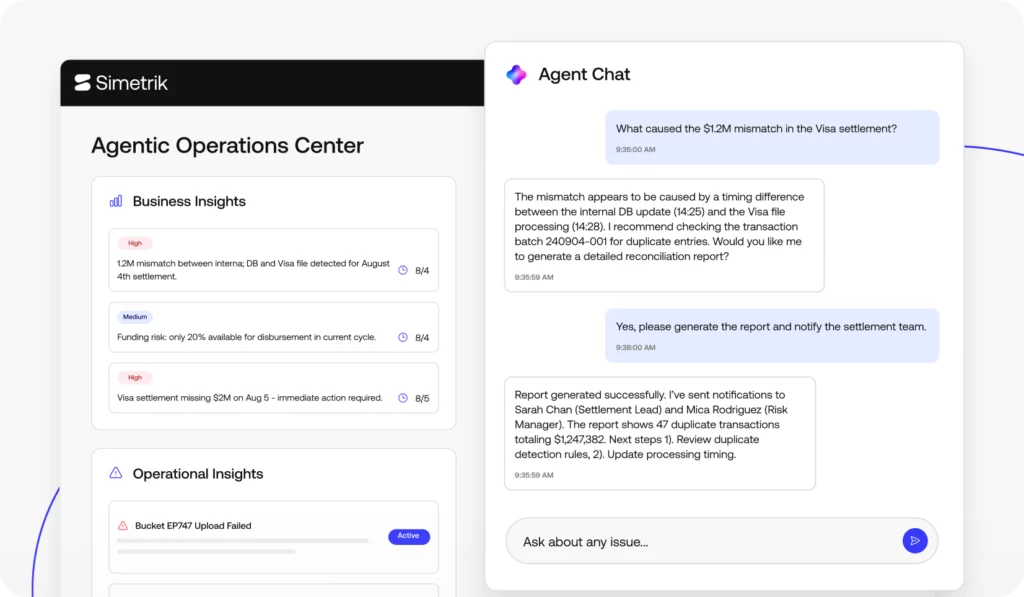
Simetrik agent chat analyzing a Visa settlement mismatch

With Simetrik, you don’t have to worry about managing a tough implementation alone. Our Visa and Mastercard solutions can be delivered in weeks, not months, with help from a dedicated onboarding team and an intelligent, guided setup assistant.

Simetrik customers can also choose from prebuilt, customizable dashboards that highlight the metrics acquirers care about the most—out-of-the-box KPIs with drill-down capability and AI-driven recommendations. 

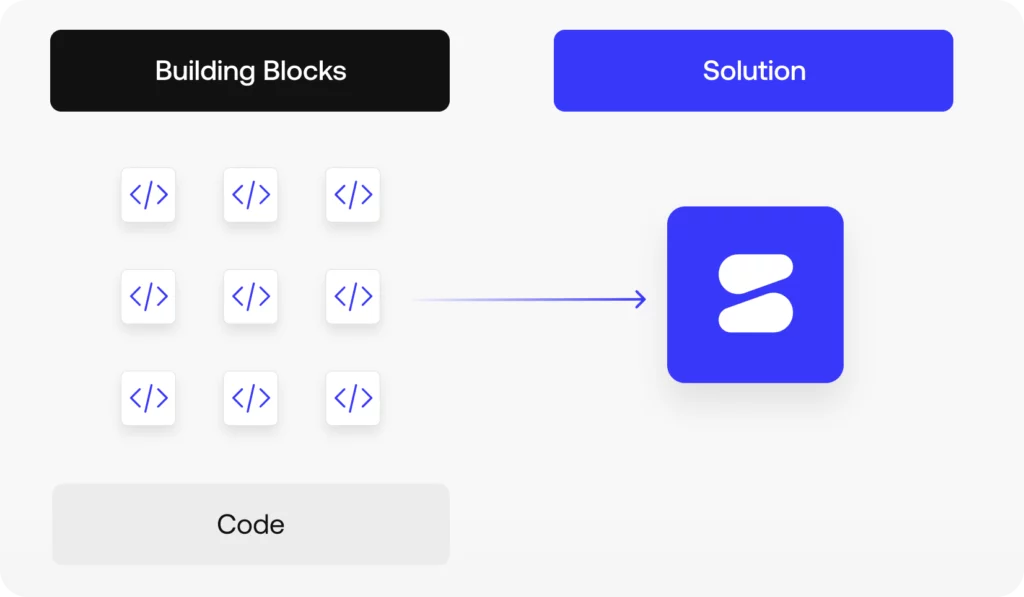
Preconfigured building blocks assembled into a Simetrik reconciliation solution

Get started with a personalized demo

Want to see Simetrik’s card network solutions in action? Request a personalized demo to explore modular workflows for authorization, clearing, settlement, fees, and disputes.

Learn more about our Visa and Mastercard solutions.